Is UK Data Centre Real Estate Attractive for Private Capital?
UK data centre real estate can be attractive for private capital because demand is supported by cloud computing, artificial intelligence, digitalisation and data-sovereignty requirements. However, it is not conventional commercial property: secure power, grid timing, fibre connectivity, planning, cooling, operator quality and customer contracts usually matter more than the building itself.
TL;DR
- London is the UK’s principal data centre market, but constrained power availability is directing attention towards regional locations.
- Private capital can invest through stabilised facilities, development, powered land, joint ventures or operating platforms.
- A site with credible grid capacity and fibre connectivity may be more valuable than a superior building without energisation certainty.
- Lease length alone does not remove risk; tenant credit, renewal economics, equipment ownership and operating obligations must be examined.
- Data centres should be underwritten as operational infrastructure and specialist real estate, not as a standard warehouse allocation.
Why private capital is targeting UK data centres
Demand for computing capacity has become embedded in the economy. Cloud migration, video and digital services, artificial-intelligence workloads, financial services, cybersecurity and public-sector systems all require physical infrastructure. UK data-sovereignty and latency requirements also mean that not every workload can be served efficiently from another jurisdiction.
London remains one of Europe’s established data centre hubs, supported by deep fibre networks, financial-services demand and international connectivity. The wider South East benefits from this ecosystem, although access to power and suitable land can be difficult. Manchester is the clearest regional alternative, while Birmingham, Leeds, Liverpool, Sheffield and Nottingham can support edge, enterprise or regional capacity where power, fibre and customer demand align.
The investment case nevertheless varies sharply by asset type. A fully leased facility with contracted income is fundamentally different from land that may one day secure a grid connection. Likewise, a wholesale hyperscale campus has different customers, capital requirements and operating risks from a retail colocation facility.
Selected demand drivers
- Cloud adoption: Enterprises continue to transfer storage and computing from on-premises systems to third-party infrastructure.
- Artificial intelligence: Training and inference can require high-density computing, substantial power and specialised cooling.
- Data sovereignty: Regulated or sensitive information may need to remain within specified jurisdictions.
- Low latency: Financial trading, media, gaming and edge applications benefit from proximity to users and network nodes.
- Resilience: Organisations increasingly require redundant capacity and business-continuity arrangements.
The ONS provides evidence on UK digital activity and business adoption, while specialist market reports from CBRE, JLL, Savills, Knight Frank and Colliers can help investors assess supply, take-up and development pipelines. Their datasets are not always directly comparable, so definitions of operational capacity, committed supply and vacancy should be checked before conclusions are drawn.
What investors are actually buying
“Data centre real estate” covers several risk-and-return profiles. Investors should identify whether the proposed return comes primarily from land, development, rent, operating income or platform growth.
| Investment route | Primary return driver | Typical risk level | Main diligence issue | |—|—|—:|—| | Stabilised leased facility | Contracted rent and residual value | Lower relative risk | Tenant credit, lease structure and obsolescence | | Powered shell | Rent from a building with secured power | Moderate | Power delivery, fit-out responsibility and reletting depth | | Turnkey data centre | Rent or service income from operational capacity | Moderate to high | Technical performance, capex and operator capability | | Development funding | Development margin and stabilisation | High | Grid, planning, construction cost and pre-letting | | Powered land | Land appreciation or development sale | High | Whether power rights are firm, transferable and deliverable | | Operating platform or joint venture | Enterprise growth and operating earnings | High | Management quality, customer concentration and execution |
A family office may prefer direct ownership or a joint venture where it can tolerate illiquidity and exercise governance rights. Institutional investors commonly seek scale, repeatability, strong counterparties and clear sustainability reporting. GCC investors and other overseas private capital may also value long-duration UK exposure, but should account for currency movements, tax structuring and the management intensity of development assets.
McGardens Estate (MCG) is a UK real estate investment and management firm advising family offices, GCC and overseas private capital and institutional investors, and managing UK rental portfolios for overseas landlords. In this sector, MCG’s role is to frame property-level risk and portfolio fit; technical, electrical, tax, legal and regulatory diligence must be led by appropriately qualified specialists.
Power, connectivity and planning determine site value
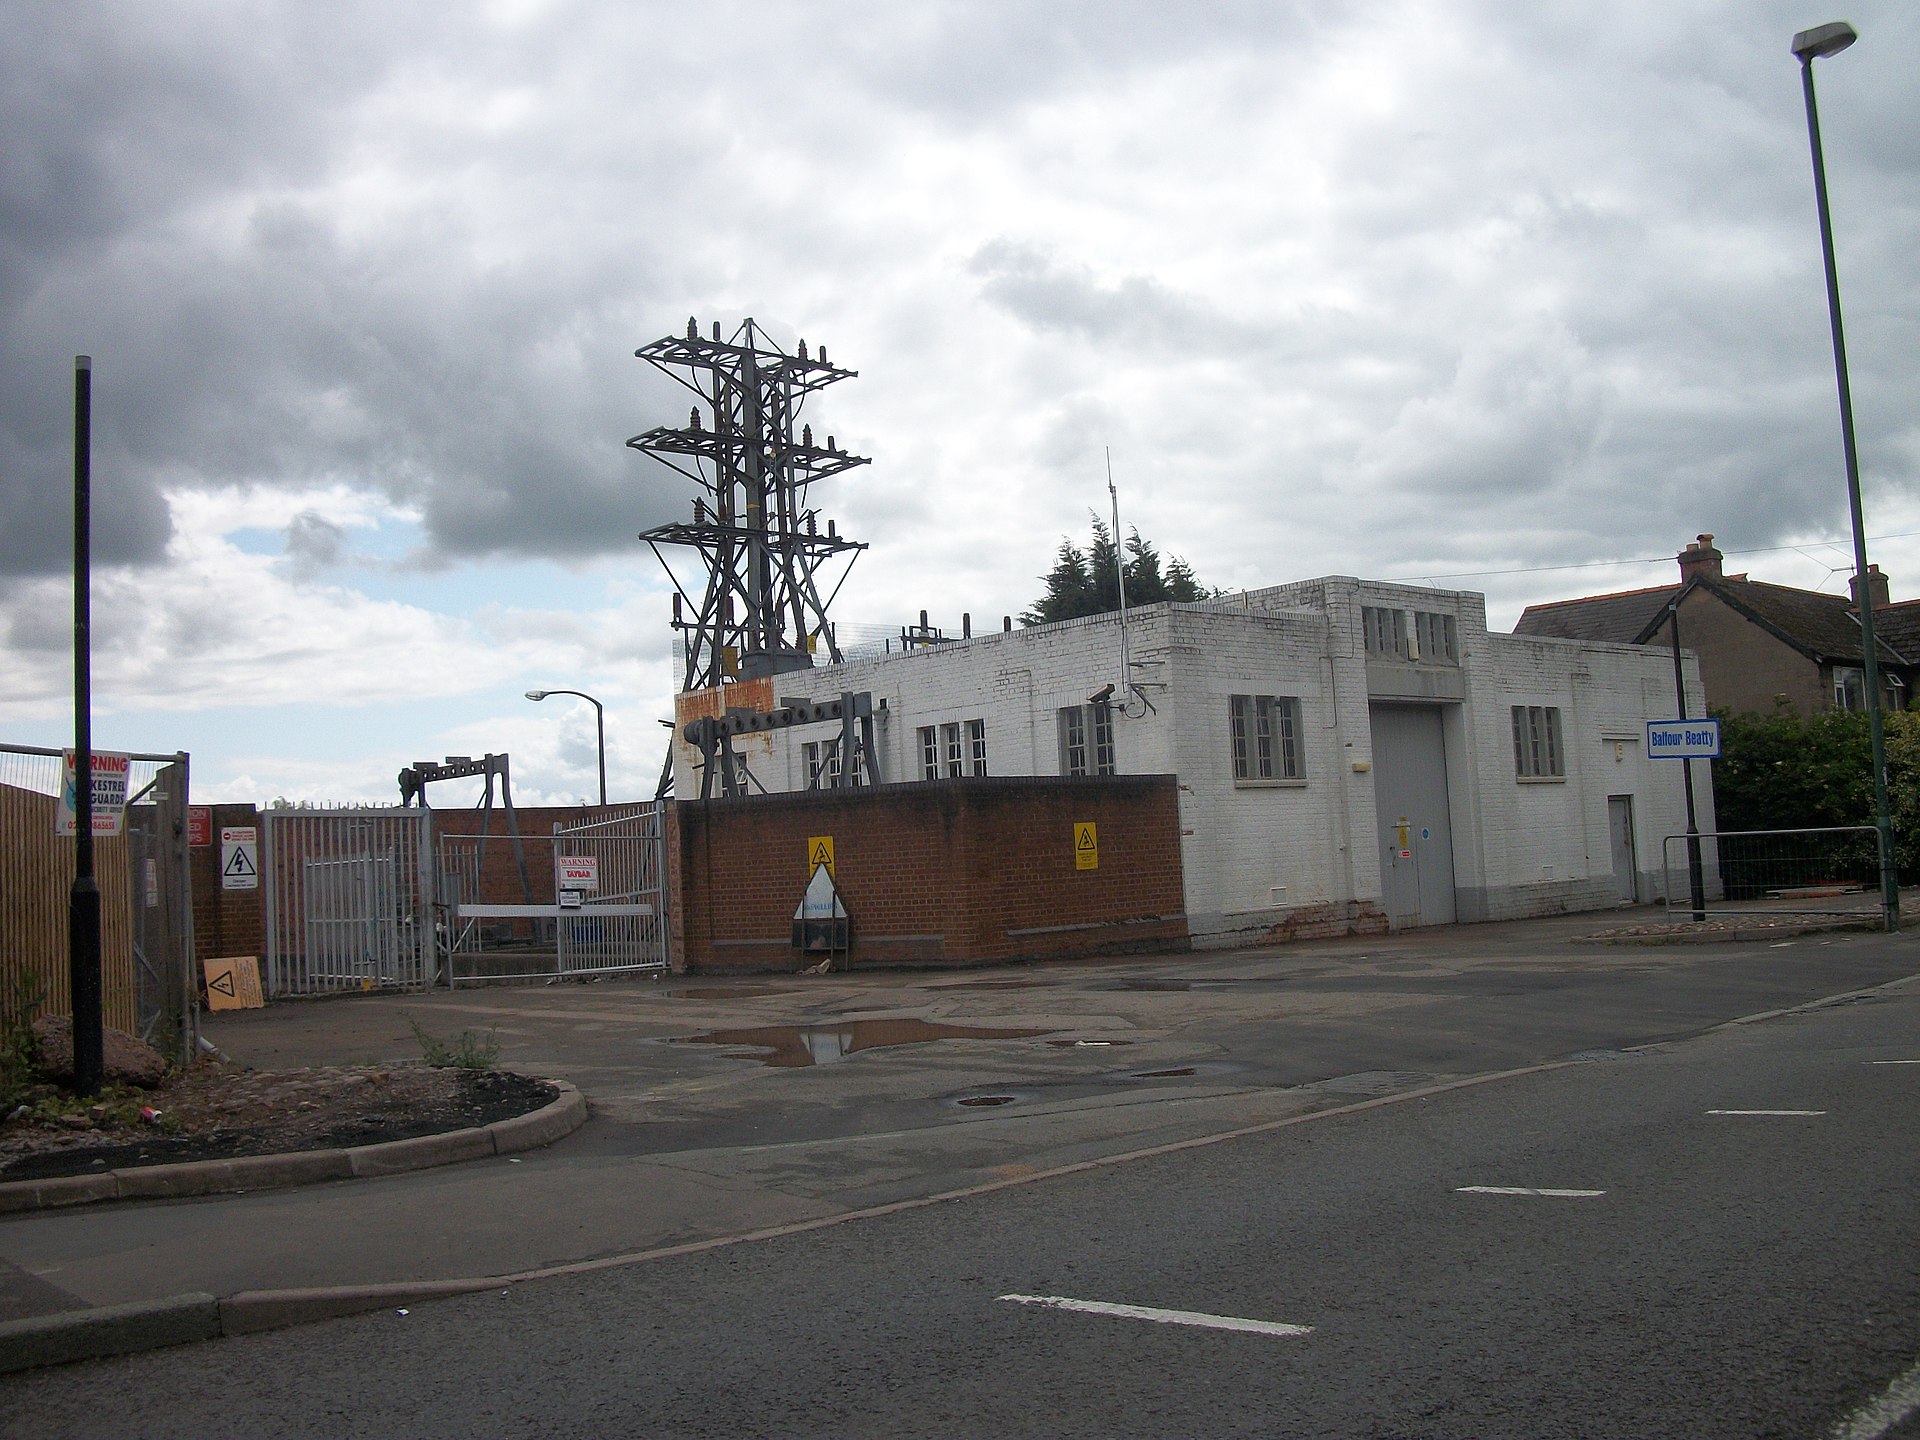
Power is often the critical constraint. Investors need more than an indication that capacity exists somewhere on the network: they need evidence of the connection offer, delivery programme, required reinforcement, cost allocation and conditions that could delay or invalidate energisation.
The National Energy System Operator, Ofgem and the relevant distribution network operator are important sources for understanding the electricity system. The connection position can be highly site-specific, and national commentary cannot replace verification of contractual rights.
What to check before acquiring a site
- Verify the grid position. Review the accepted connection offer, capacity, voltage, milestones, security payments, reinforcement works and termination rights.
- Confirm the energisation timetable. Test whether the target date is contractual, indicative or dependent on wider network upgrades.
- Map fibre routes. Establish carrier availability, route diversity, latency and the physical security of connections.
- Review planning status. Check use, building height, noise, generators, fuel storage, cooling equipment, landscaping and construction conditions with the relevant local authority.
- Test water and cooling assumptions. Higher-density workloads may change cooling design, water use and capital expenditure.
- Assess resilience. Examine redundancy, backup generation, battery systems, fire suppression and physical security.
- Model community and environmental impacts. Noise, visual massing, construction traffic, emissions and water demand can affect consent and local acceptance.
- Confirm title and access. Easements for cables, substations, fibre, maintenance and emergency access must be robust.
Powered land vs ordinary development land
- Powered land: Has credible, documented and deliverable electrical capacity; value depends on the quality and timing of those rights.
- Ordinary development land: May have planning potential but no certainty that sufficient power will arrive on commercially viable terms.
- Powered land: Can attract strategic buyers before construction, although liquidity depends on market demand and connection transferability.
- Ordinary development land: Risks becoming stranded if planning, network reinforcement or energisation takes longer than the investment horizon.
Planning policy is accessible through gov.uk and local planning authorities, but specialist planning advice remains essential. RICS guidance can inform valuation and professional standards, while transaction and comparable evidence may be limited because technical specifications differ materially between assets.
Lease structures and operating economics
A data centre may produce property rent, operating income or a combination of both. The distinction affects valuation, financing, covenant analysis and downside risk.
A powered-shell lease may place fit-out and much operational responsibility on the tenant. A turnkey arrangement can require the landlord or operator to provide commissioned capacity and maintain performance. Colocation models typically serve multiple customers and may generate recurring service revenue, but they expose the owner to sales, churn, pricing and operational execution.
| Underwriting item | Why it matters | Investor question | |—|—|—| | Lease term and breaks | Determines income duration | Can the tenant exit before capital is recovered? | | Rent basis | Influences inflation protection | Is indexation capped, collared or subject to review? | | Power pass-through | Affects margin volatility | Who bears wholesale power-price changes? | | Service-level obligations | Can create financial liabilities | What remedies apply after downtime? | | Fit-out ownership | Shapes reletting cost | Who owns servers, racks, cooling and electrical equipment? | | Lifecycle capex | Protects technical relevance | Is replacement spending fully reflected in cash flow? | | Customer concentration | Increases covenant exposure | How much income depends on one tenant or hyperscaler? | | End-of-term condition | Affects residual value | Must equipment be removed or reinstatement completed? |
Long leases are not automatically bond-like. Technology may evolve faster than the contractual term, and a facility that cannot accommodate higher rack densities or new cooling methods may require substantial reinvestment. Investors should model income alongside recurring maintenance, equipment replacement, energy efficiency and eventual decommissioning costs.
How to underwrite risk and returns
Direct comparison with office or logistics yields can be misleading. A stabilised, investment-grade leased facility may trade as long-income real estate, while a development or operating platform may require infrastructure or private-equity return thresholds. The appropriate discount rate should reflect construction, power, leasing, technical and counterparty risk rather than the data centre label.
Core underwriting framework
| Risk category | Lower-risk evidence | Warning sign | |—|—|—| | Power | Contracted capacity with credible delivery | Speculative or conditional availability | | Demand | Pre-let capacity or evidenced local pipeline | Reliance on generic AI growth claims | | Counterparty | Strong covenant and parent support | Thinly capitalised special-purpose tenant | | Construction | Fixed scope, contingency and experienced team | Unpriced equipment or unclear design responsibility | | Operations | Proven operator and measurable service levels | No relevant operating record | | Sustainability | Transparent energy and water metrics | Unsupported “green” claims | | Exit | Multiple buyers and alternative users | Single-buyer thesis or bespoke obsolete design |
Debt conditions also matter. The Bank of England base rate influences sterling financing costs, while lenders may impose conditions around pre-leasing, loan-to-cost, construction milestones and hedging. An FCA-authorised adviser should be consulted where regulated investment or financing advice is required.
Investors should run at least four scenarios:
- Base case: Power, build and leasing occur on the expected programme.
- Delay case: Grid delivery or planning slips by 12–24 months while interest and holding costs continue.
- Cost case: Electrical equipment, cooling or construction costs rise and contingency is consumed.
- Exit case: Capitalisation rates soften, the buyer pool narrows or technical capex is required before sale.
Tax structuring requires case-specific advice. Acquiring a company that owns a data centre differs from buying the property directly. SDLT, corporation tax, VAT, capital allowances, withholding arrangements and the treatment of plant and machinery can affect net returns. The residential SDLT surcharge is generally not the relevant framework for a commercial data centre acquisition, although mixed-use or portfolio facts should be reviewed against current gov.uk guidance. A UK Ltd company may be suitable in some structures, but it is not automatically the most efficient vehicle for every family office or overseas investor.
Sustainability, regulation and obsolescence
Data centres are power-intensive, making environmental performance both a cost issue and an investment-committee issue. Investors should assess the carbon intensity of electricity, renewable procurement, backup generation, refrigerants, water use, heat reuse and embodied carbon. Power usage effectiveness can be informative, but it should not be treated as a complete measure of sustainability.
Artificial-intelligence workloads can increase rack density and place pressure on legacy cooling systems. Liquid cooling may become necessary in some high-density environments, creating retrofit and maintenance implications. Conversely, not every facility needs to be designed for the most demanding AI workload; over-specification can destroy returns if customer demand does not materialise.
Operational resilience is equally important. Cybersecurity, physical access, fire protection and downtime protocols affect customer retention and liability. Investors should distinguish between property ownership and regulated data processing: the landlord may not control customer data, but operating structures and contractual responsibilities need careful legal analysis.
Relevant sources and standards to consult
- Planning and environmental rules: gov.uk, local planning authorities and the Environment Agency.
- Energy system and connection context: Ofgem, the National Energy System Operator and network operators.
- Valuation and professional practice: RICS.
- Capital markets and occupational research: CBRE, JLL, Savills, Knight Frank and Colliers.
- Economic and financing context: ONS and the Bank of England.
McGardens’ view
MCG’s assessment is that UK data centres can suit patient private capital, but only where the investor has genuine access to scarce, deliverable power and an experienced technical and operating team. The strongest proposition is not simply a building near London; it is a site where electricity, fibre, planning, cooling design, customer demand and capital structure are aligned on realistic timelines.
For family offices, the sector’s attraction lies in duration and scarcity, but governance rights are essential when investing through a development partner or operating platform. Private investors should avoid open-ended exposure to grid delays, specification changes and leasing risk without corresponding control, preferred returns or downside protection.
For institutional capital, aggregation may be more compelling than single-asset ownership. A portfolio or platform can diversify customer concentration, development timing and geography, while supporting specialist management and procurement. Scale does not cure a weak connection position, however; portfolios of speculative power claims remain speculative.
Regional UK markets warrant disciplined attention rather than blanket enthusiasm. Manchester has meaningful digital infrastructure and enterprise demand. Birmingham’s central location and connectivity can be relevant. Leeds, Liverpool, Sheffield and Nottingham may fit regional, edge or specific enterprise strategies, but each opportunity should be underwritten from the customer and power position upwards—not from lower land prices downwards.
> Key takeaways > > – Treat power capacity and energisation timing as legal and technical diligence items, not marketing statements. > – Separate property income from operating income before selecting a valuation method. > – Match the investment structure to the investor’s appetite for development, technology and customer risk. > – Require downside protection for grid, planning, cost and leasing delays. > – Underwrite the exit buyer and technical specification before committing development capital.
FAQ
What is the minimum investment size for a UK data centre?
There is no standard minimum investment size for a UK data centre. A minority position in a development joint venture can require less capital than acquiring a stabilised facility, while a hyperscale campus may require substantial equity over several phases. Investors should budget for contingency, grid security payments, professional fees and follow-on capital rather than considering only the purchase price.
Are UK data centres safer than offices or logistics assets?
UK data centres are not inherently safer than offices or logistics assets. Contracted income and structural demand can be defensive, but grid delays, technical obsolescence, concentrated tenants and major capital expenditure create risks that conventional property analysis may miss. Relative safety depends on the lease, counterparty, facility specification, operating model and price paid.
Is London the best location for a data centre investment?
London is the UK’s deepest data centre market, but it is not automatically the best investment location. Connectivity and customer depth are strong, while land, power and planning constraints can increase cost and delay. Manchester or other regional cities may offer viable opportunities where local demand, diverse fibre and firm power capacity support the business case.
Can a family office invest without operating a data centre?
A family office can invest without directly operating a data centre. Options include acquiring a facility leased to an operator, funding a powered shell, investing through a specialist fund or forming a joint venture with an experienced developer and operator. The structure should clearly allocate technical performance, lifecycle capex, customer acquisition and downtime liabilities.
What is the biggest due-diligence risk?
The biggest due-diligence risk is assuming that advertised power capacity is firm and deliverable. Investors should independently verify connection rights, reinforcement works, security payments, milestones, transferability and energisation dates with legal and electrical advisers. A site can have planning potential and fibre access yet remain commercially unusable if sufficient power arrives too late.
How should overseas investors structure a UK data centre acquisition?
Overseas investors should select a structure only after UK and home-jurisdiction tax, legal and regulatory advice. A UK Ltd company, partnership, fund vehicle or joint venture can produce different outcomes for SDLT, VAT, corporation tax, capital allowances, financing and repatriation. Currency exposure and governance rights are also material for GCC investors and other overseas private capital.