London Office Repricing: Where Are We in the Cycle?
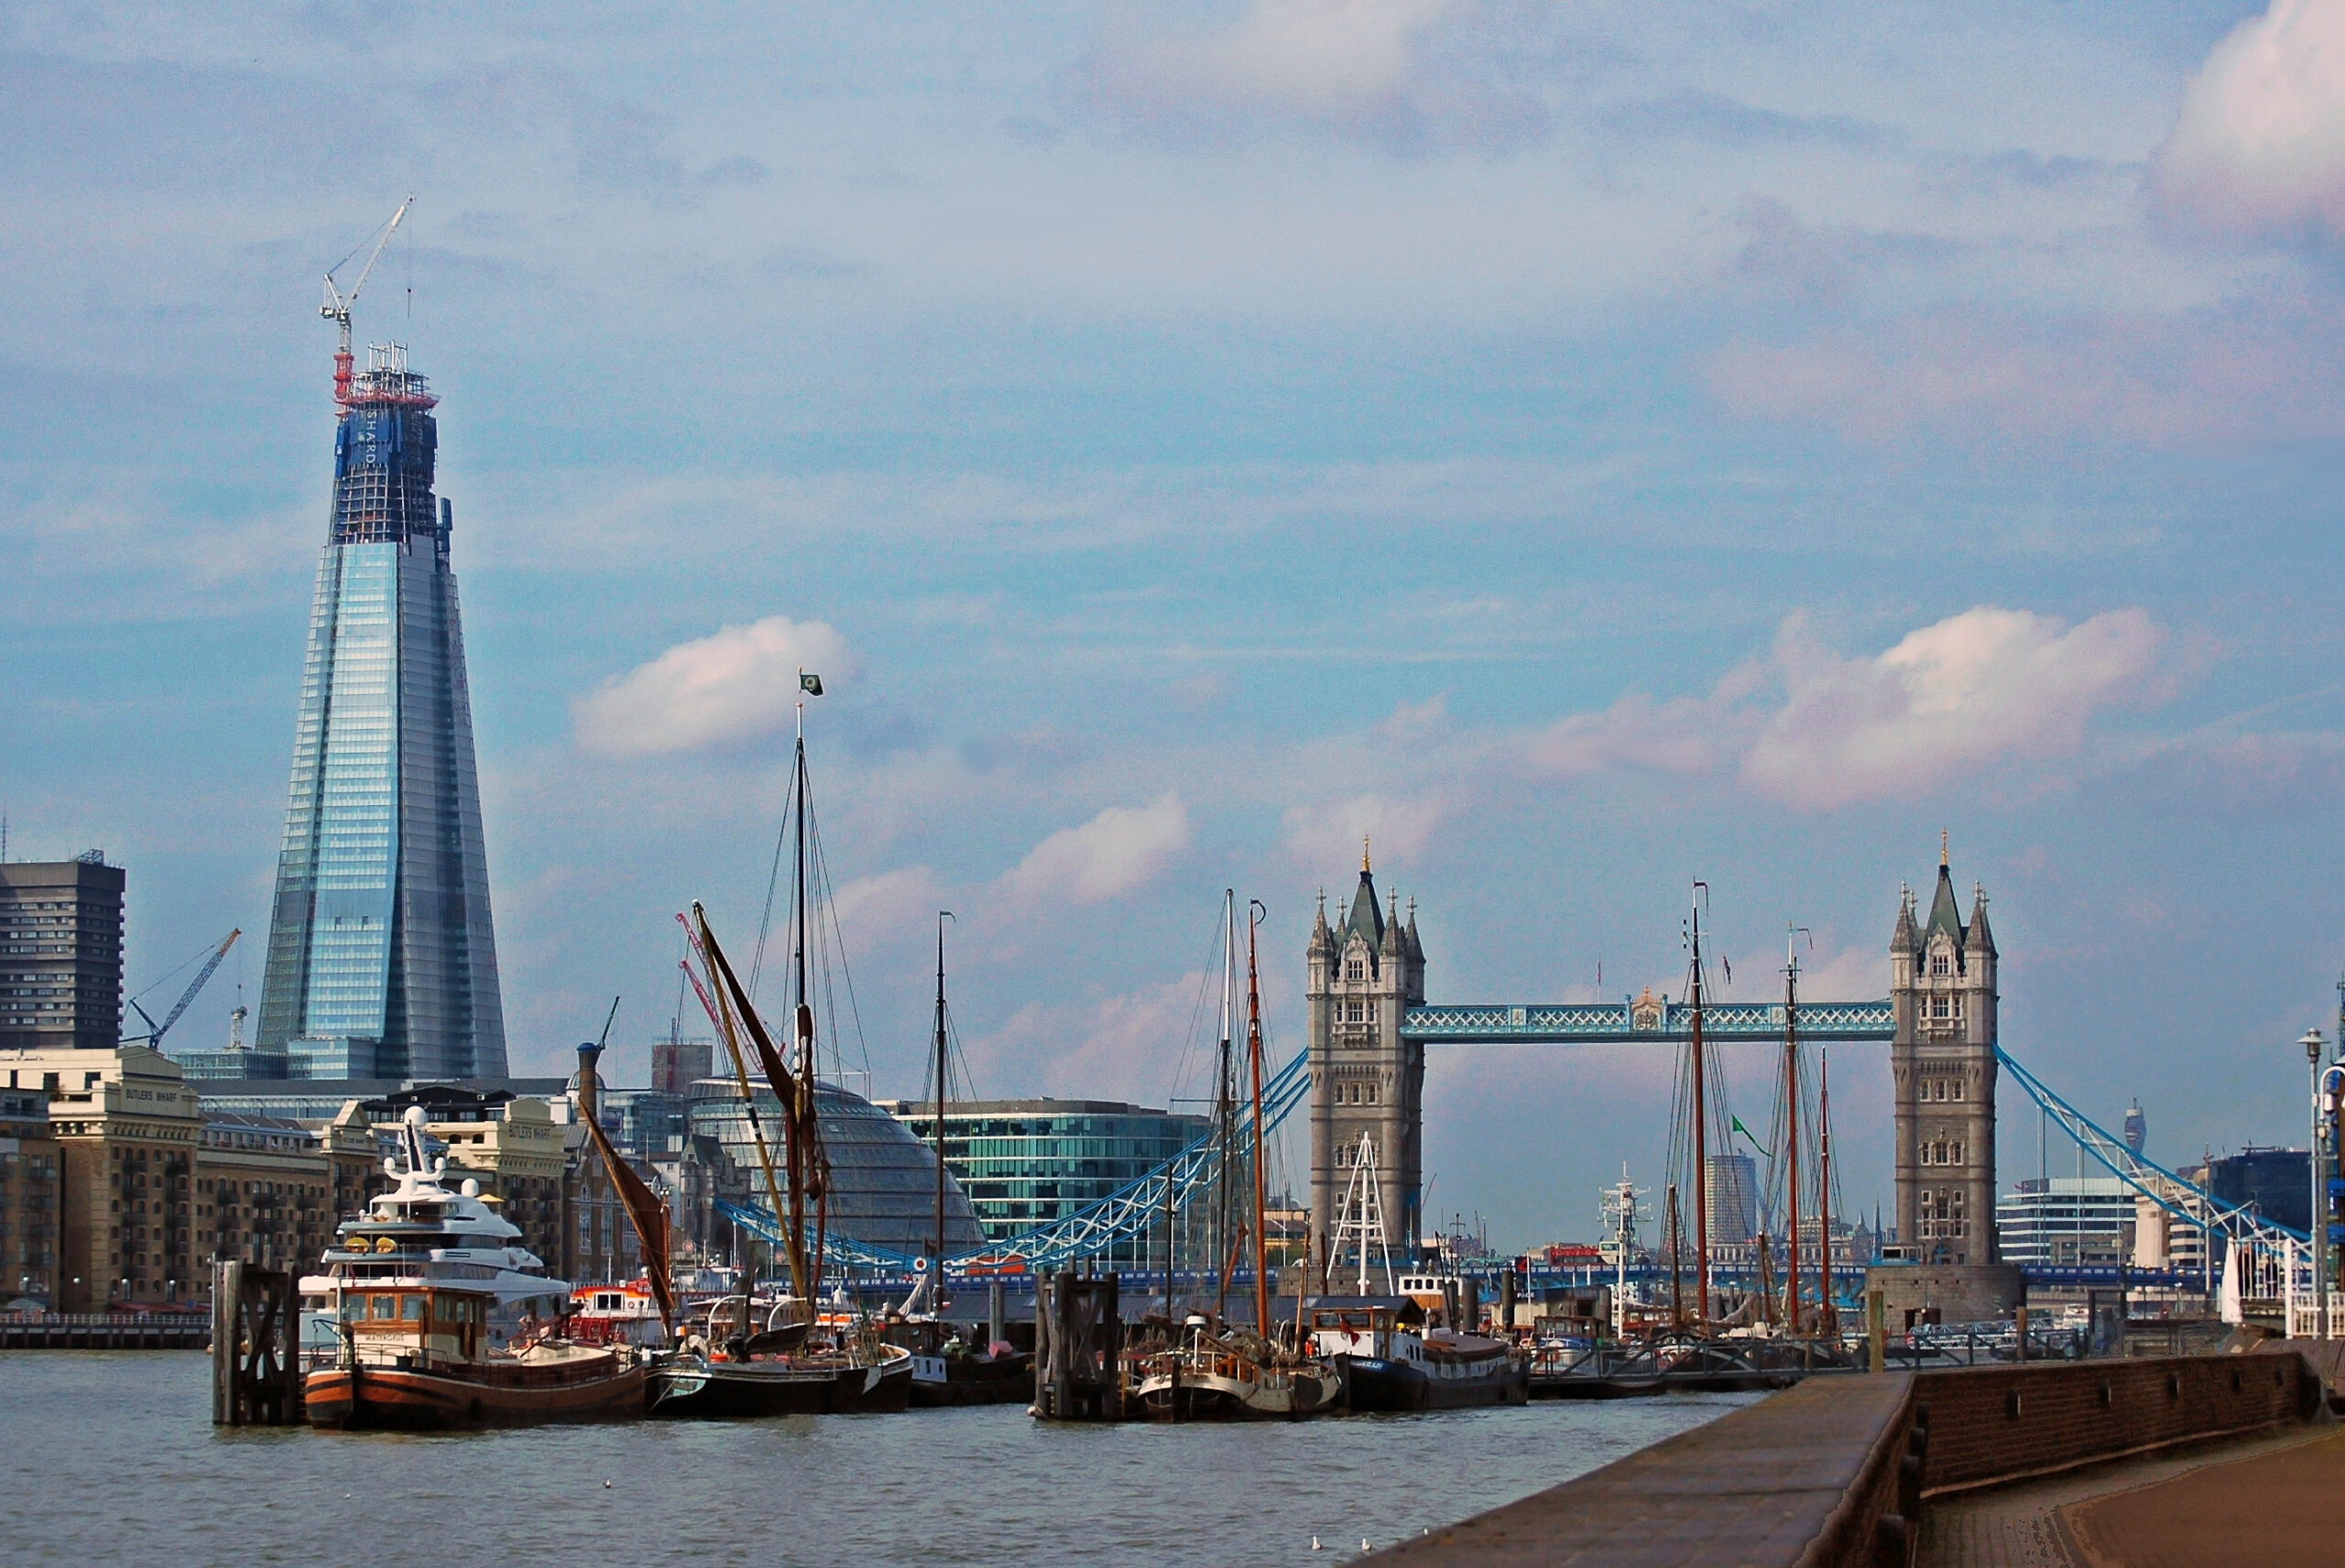
London office repricing is probably past its most indiscriminate phase, but the cycle is not complete. Prime, energy-efficient offices with strong tenants are entering stabilisation and selective recovery, while secondary buildings still face weaker liquidity, refinancing pressure and potentially substantial refurbishment costs.
TL;DR
- Higher interest rates reset London office values by increasing required returns and financing costs.
- Prime offices are stabilising before secondary stock because occupiers continue to compete for high-quality, well-connected space.
- Falling or stable benchmark rates can support pricing, but debt margins, hedging costs and lender caution remain material.
- The next phase is likely to be asset-specific rather than a uniform market recovery.
- Investors should underwrite leasing costs, energy upgrades and refinancing risk separately from headline yields.
Where London office repricing stands
London’s office market has moved through the initial shock caused by the sharp rise in the Bank of England base rate, which increased from 0.10% in December 2021 to 5.25% by August 2023. The Bank began reducing the rate in August 2024, but commercial-property financing remained materially more expensive than during the pre-2022 period.
The first stage of repricing was mechanical: government bond yields rose, borrowing costs increased and investors demanded higher property yields. The second stage involved price discovery, as sellers adjusted expectations and lenders reassessed loan-to-value ratios, interest cover and refinancing proceeds.
The market is now in a third, more selective stage. Pricing evidence is returning for some prime assets, but transaction volumes and comparable sales remain uneven. RICS market surveys, HM Land Registry records and research from firms including CBRE, JLL, Knight Frank, Savills and Colliers should be read together because no single indicator fully captures a market with relatively limited liquidity.
A practical cycle map
| Cycle phase | Typical market signal | London position | |—|—|—| | Monetary shock | Bond yields and debt costs rise rapidly | Largely passed | | Broad repricing | Property yields move out and values fall | Advanced | | Price discovery | Buyer and seller expectations begin to converge | Under way | | Stabilisation | Prime transactions establish firmer evidence | Emerging selectively | | Recovery | Liquidity broadens and values rise across more assets | Not yet market-wide |
This is therefore not a simple call that London offices have reached a universal bottom. Different buildings are at different points in the cycle.
What caused the valuation reset?
Three forces have driven the correction.
1. The risk-free rate changed
Commercial property is priced relative to other investments. When government bond yields and cash returns rose, investors required higher returns from offices. Capitalisation yields consequently moved outward, lowering values unless rent growth could offset the change.
2. Hybrid working altered occupational demand
Flexible working reduced the amount of space required by some businesses. However, it did not remove demand uniformly. Many employers consolidated into better buildings to support recruitment, attendance and corporate identity. This created a split between prime offices and less efficient, poorly located stock.
3. Capital expenditure became central to pricing
Investors now place greater weight on energy performance, amenity, building systems and the path to reletting. Older offices may require extensive investment before they can compete or meet regulatory expectations. Where refurbishment costs are uncertain, purchasers generally seek a wider margin of safety.
Statistics that frame the cycle
- December 2021: The Bank of England began increasing Bank Rate from 0.10% (Bank of England, 2021).
- August 2023: Bank Rate reached 5.25% after successive increases (Bank of England, 2023).
- August 2024: The Monetary Policy Committee reduced Bank Rate to 5.00%, beginning an easing phase (Bank of England, 2024).
- April 2023: The minimum energy-efficiency standard for most existing non-domestic private rented property in England and Wales tightened to EPC E, subject to exemptions (gov.uk, 2023).
Prime and secondary offices are following different cycles
The phrase “London office market” conceals several distinct submarkets: the City, West End, Docklands, Southbank and emerging clusters each have different occupier bases, supply pipelines and rent dynamics. Building quality introduces a further division.
> Prime vs secondary offices > > – Prime: Modern or comprehensively refurbished; strong environmental credentials; good transport access; flexible floorplates; strong tenant covenant; longer income. > – Secondary: Weaker energy performance; dated systems or amenity; near-term lease events; higher vacancy risk; uncertain refurbishment or conversion costs. > – Prime pricing: Supported by scarce supply, rental growth prospects and deeper investor demand. > – Secondary pricing: Driven increasingly by the cost of remediation, reletting and alternative use rather than historic book value.
A prime asset can stabilise even while the broader office index is falling. Conversely, a building with a nominally attractive yield may continue to lose value if the lease is approaching expiry or the required refurbishment budget rises.
This divergence also explains why quoted prime yields should not be applied mechanically to every property. A tenanted building may look inexpensive on an initial yield basis but prove costly after rent-free periods, agents’ fees, fit-out contributions, void costs and financing are included.
What would confirm that the cycle has turned?
A durable turn requires more than lower benchmark interest rates. Investors should look for several signals occurring together.
- More arm’s-length transactions: A broader set of completed sales provides stronger valuation evidence than isolated trophy deals.
- Narrower bid-ask spreads: Buyers and sellers must agree on rents, capital expenditure and exit yields.
- Improving debt availability: Higher loan proceeds, tighter margins or longer maturities would support liquidity.
- Stable prime yields: Repeated deals at similar pricing would indicate that required returns have stopped rising.
- Positive net absorption in relevant submarkets: Leasing demand must support income assumptions, not merely headline asking rents.
- A clearer refurbishment case: Contractors, lenders and investors need confidence in project costs and delivery timelines.
Market indicators to monitor
| Indicator | Positive signal | Remaining risk | |—|—|—| | Bank of England base rate | Gradual easing without renewed inflation | Long-term financing rates may remain elevated | | Investment volumes | More completed, non-distressed sales | Volumes can rise because of forced disposals | | Prime office rents | Growth supported by limited grade-A supply | Incentives may weaken effective rents | | Vacancy | Stable or falling in the target submarket | London-wide averages obscure building quality | | Debt terms | Lower all-in cost and better proceeds | Refinancing gaps remain for highly leveraged owners | | Development pipeline | Restricted future supply supports prime rents | Delayed projects may return when finance improves |
Debt will determine the pace of recovery
The equity market can accept a new valuation relatively quickly; loan books usually adjust more slowly. Many owners financed offices when rates were lower and valuations higher. At refinancing, they may encounter reduced loan proceeds because lenders apply lower values, higher interest rates and stricter interest-cover requirements.
This creates four possible outcomes: an equity injection, asset sale, loan extension or restructuring. None automatically means a distressed transaction, but collectively they can bring more stock to market and establish lower comparable values.
What to check before acquiring a London office
- Rebase the rent: Use effective rent after incentives rather than the headline figure.
- Stress the exit yield: Test slower rate cuts and a wider terminal yield.
- Cost the lease event: Include voids, service-charge leakage, fees and tenant incentives.
- Commission technical due diligence: Assess structure, plant, façade, lifts and energy performance.
- Model the EPC pathway: Identify required works, timing and applicable exemptions under current rules.
- Review tenant covenant: Consider business concentration, break options and guarantor strength.
- Test refinancing: Model lower leverage and higher debt margins at maturity.
- Examine alternative use carefully: Planning, daylight, floor depth, fire safety and build cost can prevent apparently straightforward conversion.
FCA regulation may also be relevant where investment structures, financial promotions or regulated financing activities are involved. Specialist legal, tax, planning and lending advice should be obtained before execution.
Implications for different capital types
Family offices, GCC investors and institutional investors often approach this stage of the cycle differently.
Family offices may benefit from flexible holding periods and the ability to acquire without maximum leverage. That can be valuable where refurbishment takes time or leasing assumptions require patience. GCC investors may also find sterling-denominated assets attractive strategically, but currency exposure should be assessed separately from property returns.
Institutions generally require clearer liquidity, governance and sustainability evidence. They may favour larger, prime assets or Build-to-Rent and PBSA where income characteristics fit their mandates. By contrast, operational residential strategies—including HMOs in cities such as Manchester, Leeds, Liverpool, Birmingham, Sheffield and Nottingham—carry different management, regulatory and liquidity risks from London offices and are not direct substitutes.
Ownership structure matters as well. A Ltd company, partnership, offshore vehicle or institutional fund can produce different tax, reporting and financing consequences. Commercial property acquisitions are subject to non-residential SDLT rules; the residential SDLT surcharge should not simply be applied to an office transaction, although mixed-use and conversion cases require careful classification. Investors should verify the prevailing position on gov.uk and obtain UK tax advice.
McGardens Estate (MCG) is a UK real estate investment and management firm advising family offices, GCC and overseas private capital and institutional investors, and managing UK rental portfolios for overseas landlords.
McGardens’ view
MCG’s assessment is that London office repricing has moved beyond the initial interest-rate shock, but it has not yet developed into a broad recovery. The investable opportunity is increasingly found in the gap between buildings with curable problems and those facing structural obsolescence.
That distinction depends on execution rather than yield alone. An office with short income, dated plant and a weak EPC may offer a compelling basis if it occupies a strong location, has flexible floorplates and can be upgraded within a controlled budget. The same headline discount is inadequate where the building cannot economically satisfy modern occupier expectations.
Prime assets are likely to lead because they benefit from both capital scarcity and occupational scarcity. Secondary values may continue to fall even as prime yields stabilise, particularly where owners have not recognised the full cost of refurbishment, incentives and finance.
For family offices and long-duration capital, the current phase can offer attractive entry points, but only where the business plan is funded through completion and does not depend on rapid yield compression. The prudent underwriting case assumes a slower recovery, conservative leverage and an exit supported by income quality rather than monetary policy alone.
> Key takeaways > > – London office repricing is advanced, not finished. > – Prime stabilisation should not be mistaken for a market-wide bottom. > – Refinancing events are likely to create further acquisition opportunities. > – Building quality, lease structure and capital expenditure now matter more than postcode-level averages. > – Returns should be underwritten to durable income, not an assumed return to pre-2022 interest rates.
FAQ
Have London office values reached the bottom?
London office values have not reached a single, verifiable market-wide bottom. Prime, well-let and energy-efficient buildings may have stabilised, while offices requiring substantial capital expenditure or facing near-term vacancies can still reprice. A convincing bottom would require broader transaction evidence, narrower bid-ask spreads and improved financing conditions across more than trophy assets.
Are prime London offices a good investment now?
Prime London offices can offer attractive risk-adjusted opportunities where the income, tenant covenant and acquisition basis are robust. Investors should not rely solely on expectations of falling interest rates. Effective rents, lease incentives, debt costs, sustainability credentials, future supply and the exit buyer pool should support the investment case independently.
Will Bank of England rate cuts increase office values?
Bank of England rate cuts can support office values, but they do not guarantee an immediate recovery. Commercial mortgage pricing also reflects gilt and swap rates, lender margins, leverage and asset risk. Values are more likely to improve sustainably when cheaper finance coincides with strong leasing, stable yields and greater transaction liquidity.
What is the main risk in buying a secondary London office?
The main risk is underestimating the combined cost of obsolescence and lease-up. Refurbishment, energy upgrades, professional fees, void periods, rent-free incentives and financing can consume an apparent discount. Some buildings also have physical or planning constraints that make residential conversion or repositioning uneconomic.
Should overseas investors hedge sterling exposure?
Overseas investors should assess sterling exposure independently from the property’s expected return. Hedging can reduce currency volatility but introduces cost, collateral and maturity considerations. GCC investors and other dollar-based buyers should compare hedged and unhedged cash flows under several exchange-rate scenarios rather than treating currency movements as an incidental gain.
How should family offices finance a London office acquisition?
Family offices should use leverage that remains serviceable under slower leasing, higher refinancing rates and a delayed exit. Conservative debt can preserve flexibility during refurbishment and reduce the risk of forced sales. Loan maturity, hedging, covenants and interest-cover tests are as important as the initial margin or headline loan-to-value ratio.