Which UK Regional Cities Have the Best Rental Growth Potential?
McGardens’ directional assessment places Manchester first, followed by Birmingham and Leeds, based on employment depth, rental demand and supply conditions. Outcomes can vary materially by neighbourhood, building and property type. Nottingham, Sheffield and Liverpool may offer stronger entry-income opportunities in selected cases, but investors should expect more neighbourhood-level variation and greater sensitivity to local supply.
TL;DR
- McGardens’ assessment places Manchester first for its balance of economic depth, tenant demand, liquidity and institutional validation.
- Birmingham ranks second in this assessment because of its scale, connectivity and broad employment base, although apartment supply must be assessed carefully.
- Leeds has durable demand across financial services, legal, digital, healthcare and higher education.
- Nottingham, Sheffield and Liverpool may provide higher starting income in selected cases, but selection at submarket and asset level is critical.
- Rental growth should be underwritten from affordability, competing supply and net operating income—not recent headline rent rises alone.
Ranking methodology
This ranking assesses rental growth potential rather than simply identifying the highest current gross yield. The distinction matters: a high initial yield can reflect low liquidity, weak capital values, intensive management or elevated building-level risk.
McGardens considers five factors:
- Employment and population depth: diversified job creation supports household formation and reduces dependence on one employer or sector.
- Rental demand: graduate retention, student populations, inward migration and the size of the professional renter market affect occupancy and pricing power.
- Supply pressure: development pipelines, planning constraints and the condition of existing stock influence how quickly rents can rise.
- Affordability headroom: rents cannot sustainably outpace local earnings indefinitely; rent-to-income pressure is a central constraint.
- Investment liquidity: established transaction markets, lender appetite and participation by Build-to-Rent investors improve exit options.
The ranking is McGardens’ directional editorial assessment, not a forecast of a precise annual growth rate. Outcomes will vary by submarket, building and acquisition basis. ONS rental indices are valuable at national, regional and local-authority level, while Rightmove, Zoopla and HomeLet-type asking-rent measures can provide more immediate signals. These datasets use different methodologies and should not be treated as interchangeable.
UK regional cities ranked
| Rank | City | Rental growth potential | Typical income profile | Principal support | Main risk | |—:|—|—|—|—|—| | 1 | Manchester | Very strong | Asset-specific; verify achieved rent and all operating costs | Employment depth, graduate retention, international profile | New-build pricing and concentrated apartment supply | | 2 | Birmingham | Very strong | Asset-specific and materially dependent on district | Scale, connectivity, professional demand | Micro-location quality and competing pipeline | | 3 | Leeds | Strong | Varies across professional, student and conventional rental stock | Diverse economy and large graduate market | City-centre supply and service-charge pressure | | 4 | Nottingham | Strong | Can vary materially by asset type and operating model | Affordability, universities, healthcare and life sciences | Local licensing and HMO operating complexity | | 5 | Sheffield | Moderately strong | Dependent on location, property format and tenant segment | Relative affordability, advanced manufacturing, universities | Slower liquidity in some submarkets | | 6 | Liverpool | Moderately strong | Headline income must be tested against building and operating costs | Low entry cost, visitor economy, universities | Highly variable building quality and local supply |
These income descriptions are broad editorial observations, not valuations or guaranteed returns. Investors should calculate returns from the actual purchase price and achieved rent, deducting voids, management, maintenance, insurance, service charges, tax and financing costs.
Comparison box: growth-led versus income-led markets
- Manchester and Birmingham: deeper occupational markets and stronger institutional liquidity; usually higher entry prices.
- Leeds: balanced growth-and-income characteristics; established professional and student demand.
- Nottingham and Sheffield: comparatively affordable entry points; more dependence on exact neighbourhood and property format.
- Liverpool: potentially higher headline income in selected stock; greater need for building, tenure and supply due diligence.
1. Manchester: McGardens’ strongest all-round rental growth case
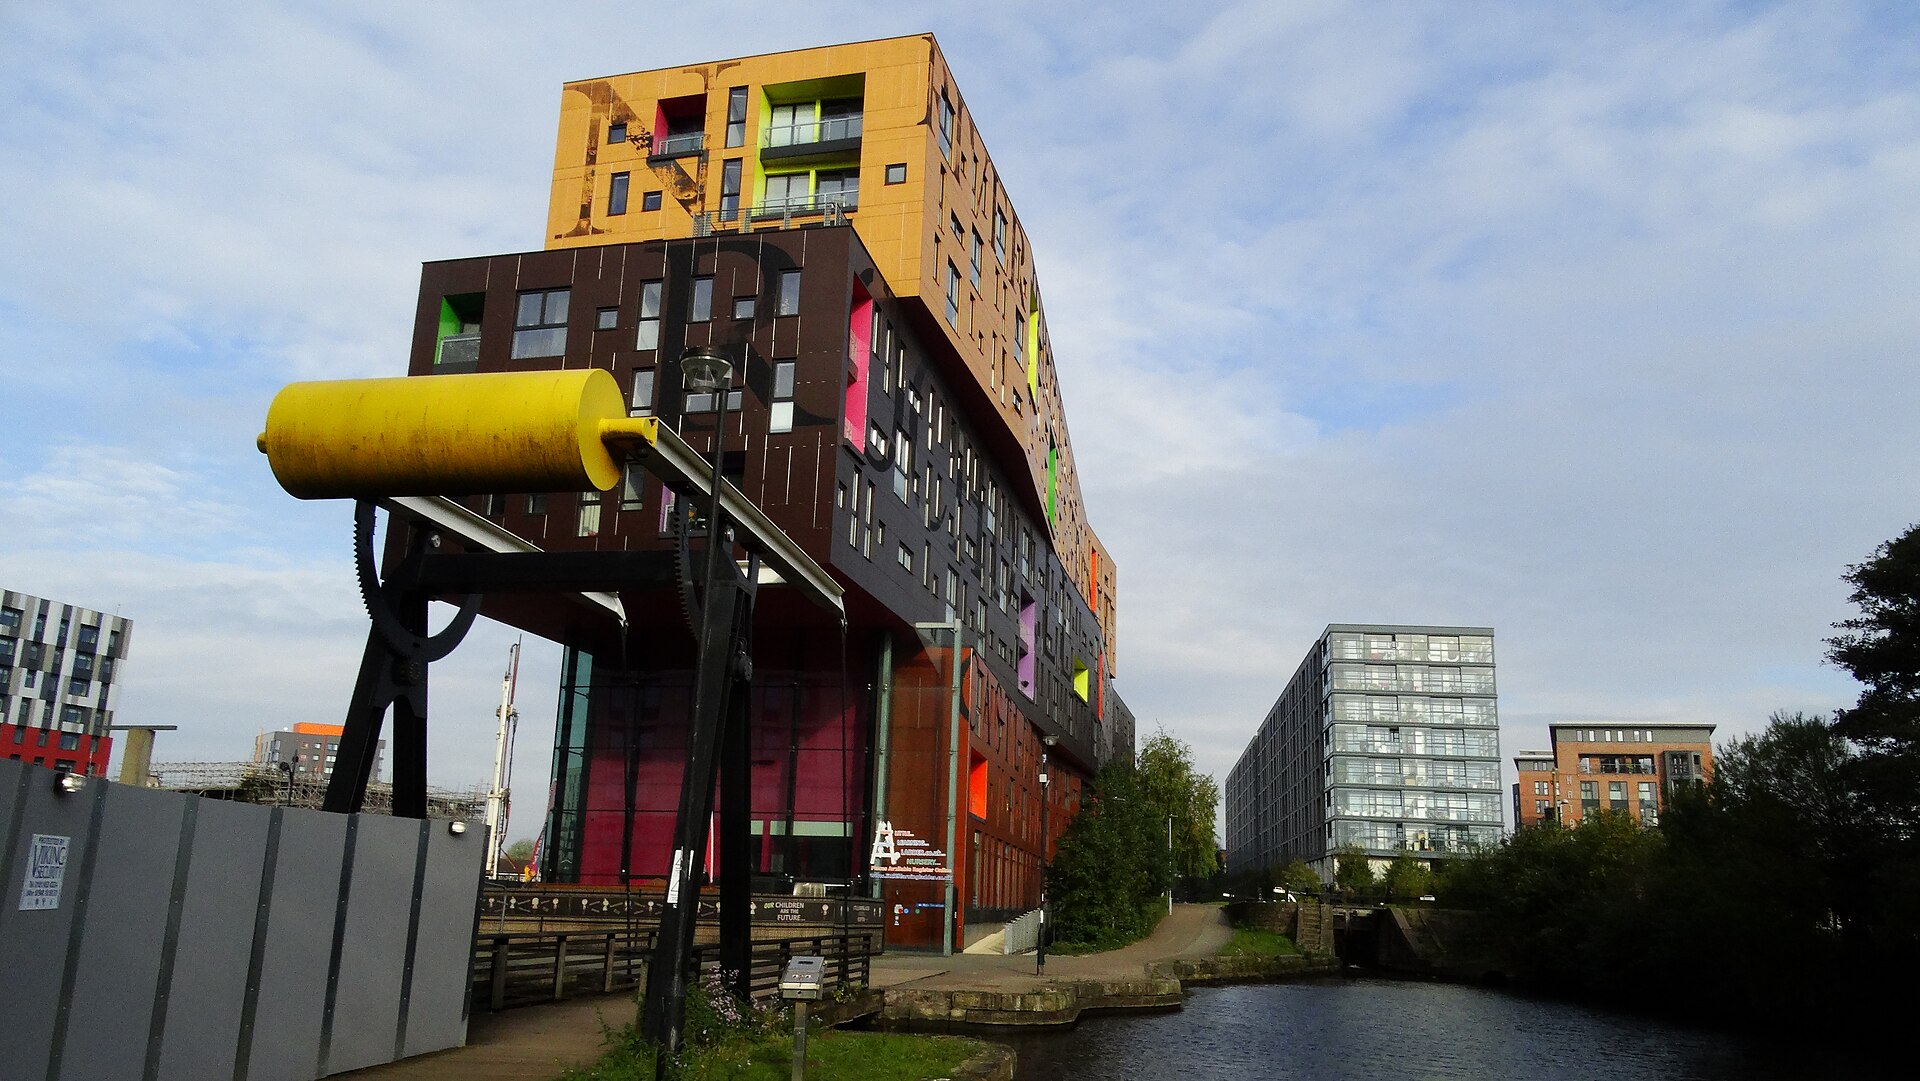
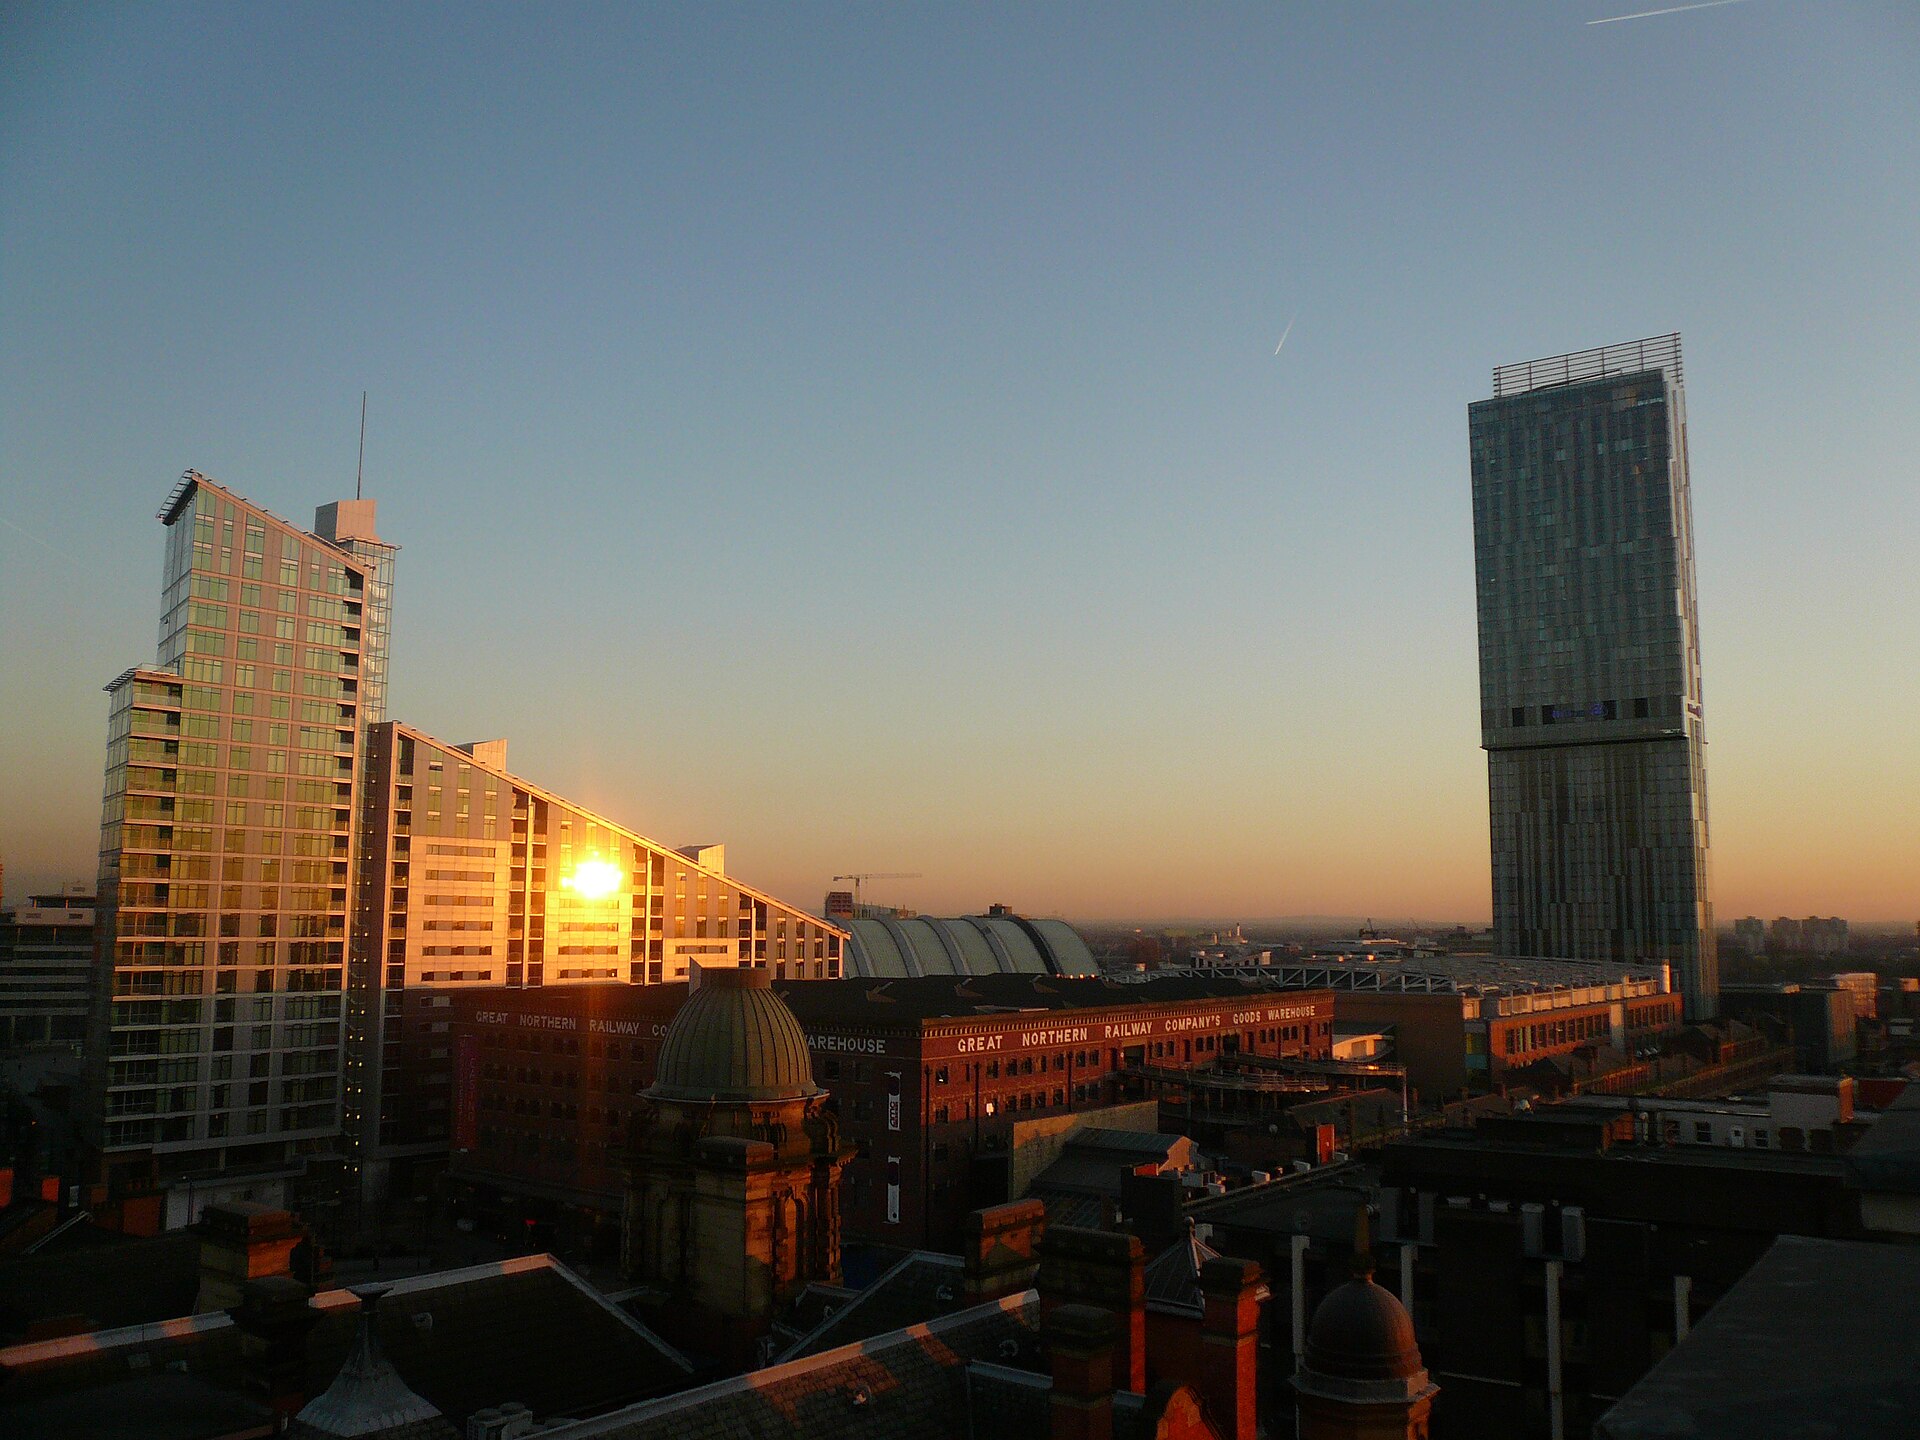
Manchester has the most mature investment proposition among the six cities in McGardens’ assessment. Its strengths include a large city-region economy, strong university ecosystem, graduate retention, transport connectivity and concentrations in technology, media, professional services, financial services and life sciences.
The city also has substantial Build-to-Rent participation. That is both validation and competition: institutional operators demonstrate confidence in long-term tenant demand, but professionally managed schemes can raise residents’ expectations and pressure undifferentiated private landlords.
Rental growth potential is strongest where employment access, transport, amenities and scarcity align. Manchester city centre, Salford and selected neighbourhoods across Greater Manchester should not be treated as one market. Investors must compare the local delivery pipeline with the realistic tenant pool for each price point.
What to check in Manchester
- Competing Build-to-Rent and new-build completions within the letting catchment.
- Service charges and planned major works in apartment blocks.
- Lease terms, ground rent provisions and EWS1 or wider building-safety documentation where relevant.
- Achieved rents for comparable units rather than developer projections.
- Access to employment nodes, tram stops and established amenities.
2. Birmingham: scale and connectivity support demand
Birmingham’s case rests on scale. It has a large and diverse population, major universities and employment across professional services, financial services, healthcare, advanced manufacturing and the public sector. Regeneration and connectivity improvements can deepen demand, but investors should avoid basing an acquisition solely on a future infrastructure milestone.
The rental market is fragmented. The city centre, Jewellery Quarter, Digbeth, Edgbaston and outer districts serve different tenant groups and display different levels of supply, affordability and liquidity. A new apartment may attract mobile professionals, while a suburban house may offer lower turnover and a broader family tenant pool.
Birmingham therefore ranks highly in McGardens’ assessment for portfolio-scale opportunity but requires disciplined micro-location analysis. Institutional capital may favour Build-to-Rent or standing multifamily assets, while family offices can access smaller blocks, suburban rental housing or mixed-use opportunities.
3. Leeds: a balanced professional rental market
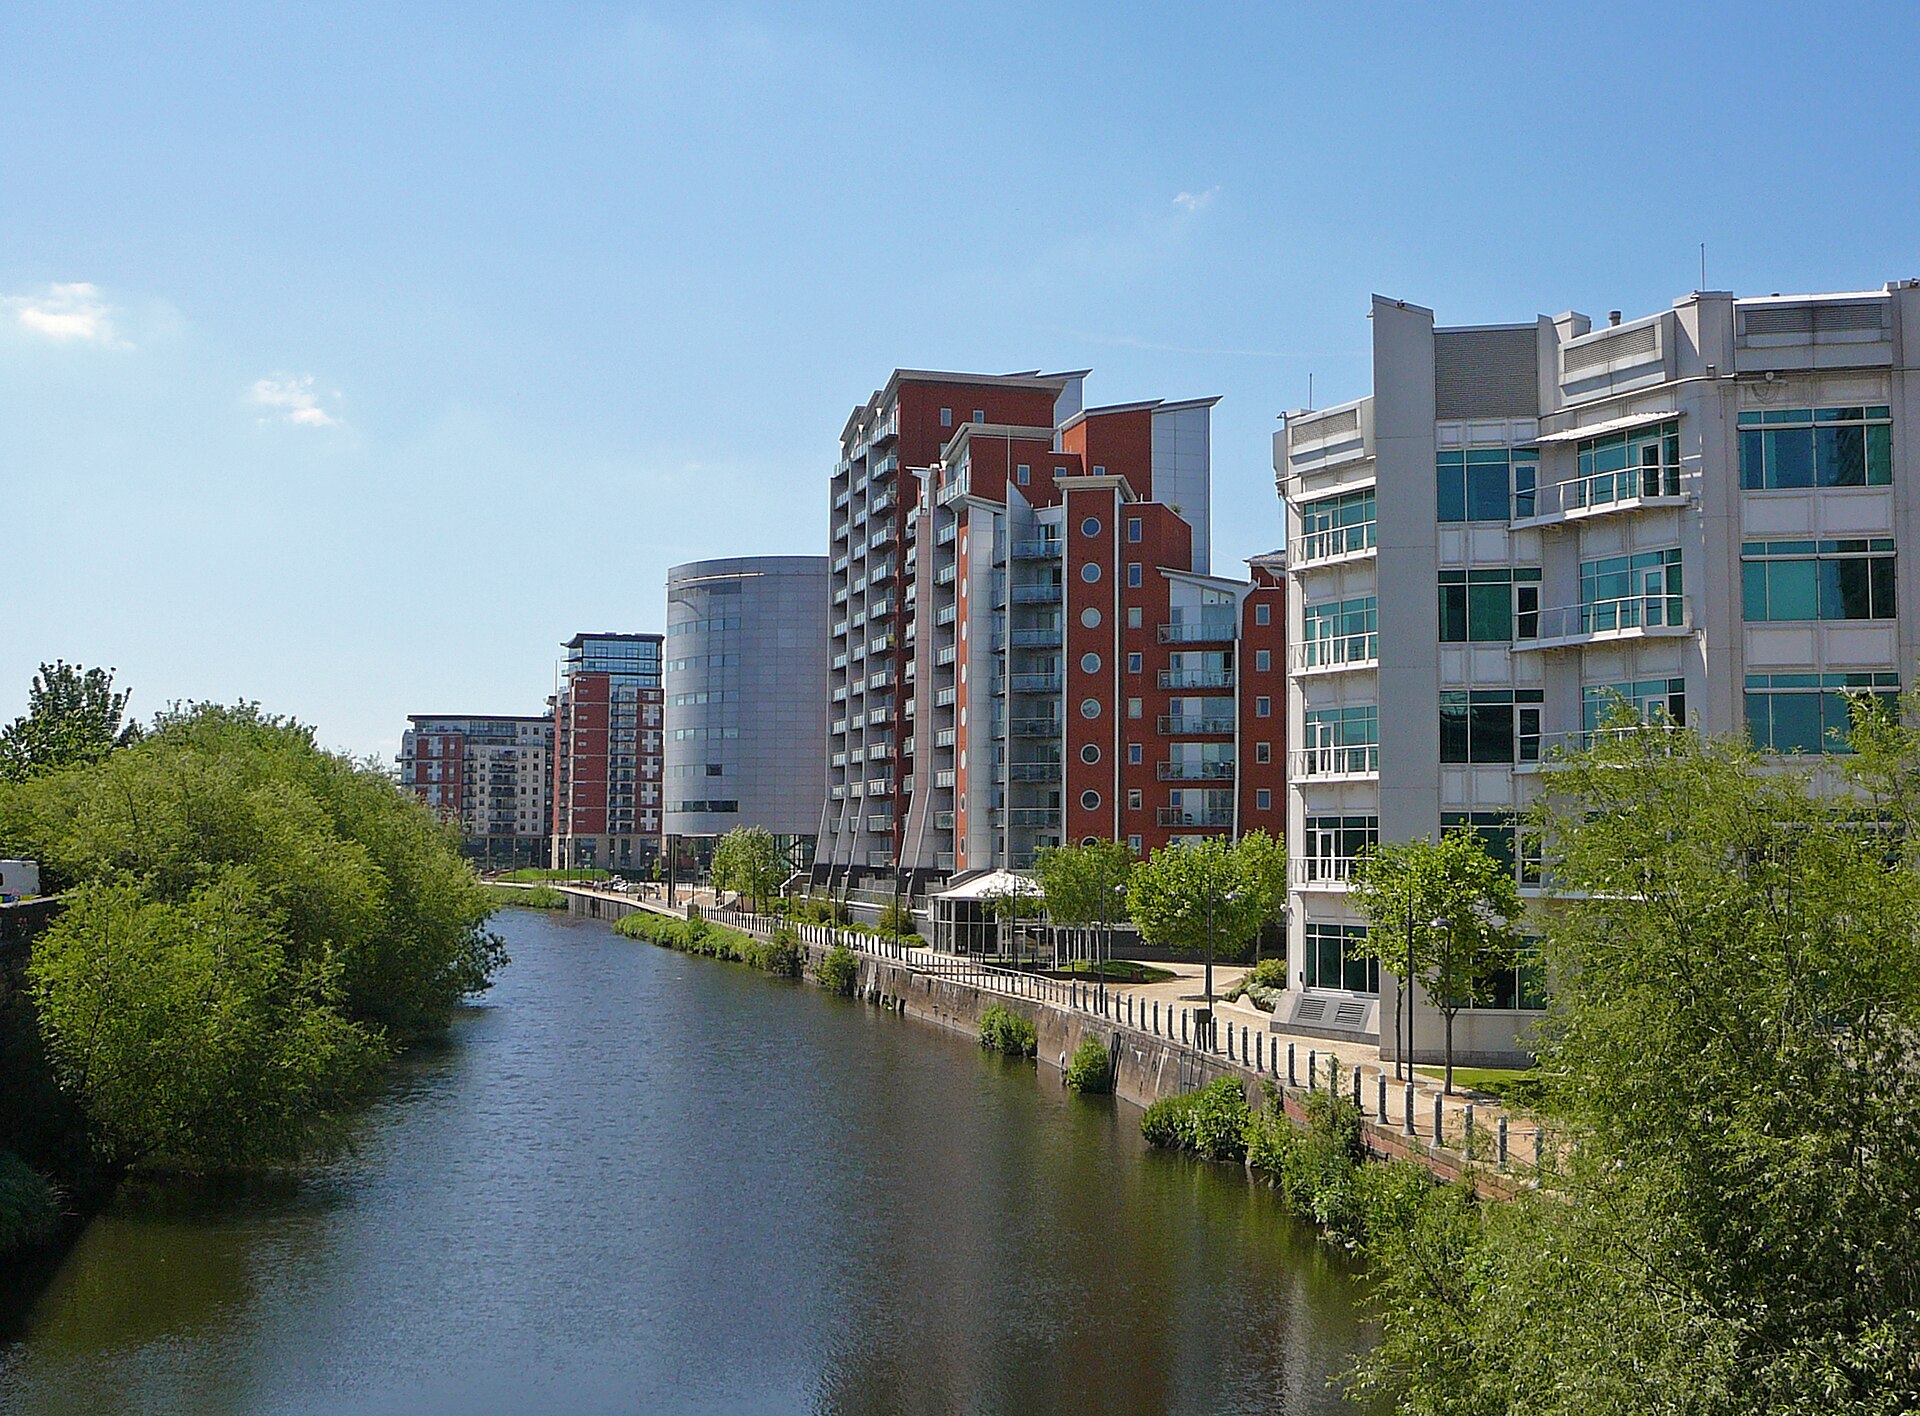
Leeds combines a substantial employment base with one of the UK’s largest higher-education clusters. Financial and professional services, legal, digital, healthcare and public-sector employment support demand beyond the student market.
The city is particularly relevant to investors seeking a balance between income and long-term rental growth. Central Leeds attracts professionals, while districts such as Headingley and Hyde Park have deep student demand. These submarkets should not be blended in underwriting: PBSA, HMOs and conventional private rented apartments have different lease structures, operating costs and regulatory exposures.
Supply remains the key variable. Investors should map consented, under-construction and recently completed units, not simply the visible pipeline. A large theoretical pipeline may be delayed, whereas several near-complete schemes can affect rent-free incentives and occupancy immediately.
4. Nottingham: affordable entry with diversified demand
Nottingham benefits from two major universities, the Queen’s Medical Centre, public-sector employment and growing life-sciences and technology activity. Its relatively accessible purchase prices may support competitive gross yields in individual acquisitions, but the outcome depends on the price paid, achieved rent, voids and operating costs.
Demand is broad but highly localised. The city centre, Beeston, Lenton, West Bridgford and other districts attract different tenant cohorts. HMOs can produce attractive headline income, yet licensing, fire safety, planning, management intensity and utility costs can materially reduce net returns.
Nottingham’s rental growth potential is credible where conventional housing supply is constrained and rents remain aligned with local earnings. Family offices should distinguish scalable, professionally manageable assets from high-yield stock that depends on intensive local operations.
5. Sheffield: affordability and economic transition
Sheffield offers lower entry costs than Manchester or Birmingham in many comparable property types. Its universities, teaching hospitals, advanced manufacturing base and developing technology ecosystem create several demand anchors.
The city may appeal to investors seeking defensive affordability rather than premium-city pricing. Houses in established neighbourhoods can serve families and professionals, while student areas support HMOs and PBSA. The trade-off is that transaction liquidity and rental depth can vary significantly outside the strongest districts.
Rental growth is most sustainable where tenants have multiple employment options and the property is not reliant on one narrow audience. Underwriting should therefore test demand from professionals and families as well as students, particularly for assets outside the core university catchments.
6. Liverpool: potentially higher income, wider dispersion of outcomes
Liverpool is often marketed as a higher-yield regional market because of comparatively low acquisition costs and demand associated with its student population, healthcare and visitor economy. Realised returns can vary materially by building, purchase price, achieved rent, voids, service charges and other operating costs. The city also presents a wide dispersion between strong and weak investments.
Building quality, leasehold terms, service charges and local apartment supply require close attention. Investor-led new-build schemes may quote attractive yields that depend on optimistic rents, low assumed voids or temporary guarantees. Rental guarantees are only as strong as the covenant providing them and should not substitute for market evidence.
Liverpool can suit income-focused investors with robust local management and detailed due diligence. For institutional capital, scale, operational control and asset quality are likely to matter more than the highest possible unit-level gross yield.
What could change the ranking?
Rental growth is cyclical. The ranking can change as financing costs, construction activity, employment and affordability evolve.
Statistics and policy signals to monitor
- Private rents: the ONS Price Index of Private Rents provides the principal official measure of rental inflation across the UK and its regions (ONS, ongoing monthly series).
- House prices: HM Land Registry’s UK House Price Index tracks completed transaction prices, although publication lags the live market (HM Land Registry, ongoing monthly series).
- Interest rates: the Bank of England base rate affects mortgage pricing, development viability and investor required returns (Bank of England, ongoing).
- Sales and letting conditions: RICS surveys provide timely evidence from chartered surveyors on tenant demand, landlord instructions and price expectations (RICS, ongoing).
- Asking-market evidence: Rightmove and Zoopla provide useful current indicators, but asking rents are not the same as achieved rents.
A falling Bank of England base rate could improve acquisition liquidity and development viability. That may support values, but it can also unlock delayed supply. Conversely, sustained high borrowing costs may restrict new construction while forcing leveraged landlords to sell—tightening rental availability but increasing acquisition opportunities.
Tax also affects portfolio strategy. Purchases of additional dwellings can attract the higher SDLT rates applicable in England and Northern Ireland; current thresholds and surcharges should always be checked on gov.uk. A Ltd company can be appropriate for some investors, but incorporation does not remove SDLT, tax, financing or compliance costs. Regulated mortgage advice should come from an FCA-authorised adviser.
How to underwrite a regional rental acquisition
- Define the tenant precisely. Separate professionals, families, students, key workers and short-stay demand.
- Use achieved comparables. Obtain recent tenancy evidence for genuinely comparable size, condition, furnishing and location.
- Map competing supply. Include Build-to-Rent, PBSA, conversions, conventional buy-to-let and new housing delivery.
- Stress-test affordability. Compare proposed rent with local earnings and test lower rental growth, voids and incentives.
- Calculate net operating income. Deduct management, maintenance, insurance, compliance, service charges and realistic voids.
- Review regulation. Check selective licensing, additional HMO licensing, Article 4 directions, planning use and building safety.
- Stress financing. Model interest rates above the initial mortgage rate and allow for refinancing fees and valuation risk.
- Plan the exit. Assess whether the likely buyer is an owner-occupier, another landlord, a family office or institutional capital.
McGardens’ view
The strongest regional rental strategy is not to buy the city with the fastest recent rent increase. Exceptional short-term growth often follows an acute supply shock and can be followed by affordability resistance, renewed development or tenant migration to adjacent districts.
In McGardens’ editorial assessment, Manchester offers the clearest institutional proposition because occupational demand, transaction liquidity and the Build-to-Rent market are comparatively deep. Birmingham has similar scale advantages but requires greater selectivity around apartment supply and neighbourhood execution. Leeds is assessed as the most balanced alternative for investors seeking economic diversity without Manchester-level entry pricing. Performance in all three cities will vary by submarket and acquisition basis.
Nottingham and Sheffield merit consideration where the strategy prioritises affordable rents and resilient occupancy. In McGardens’ general assessment, selected Liverpool properties may offer stronger headline income, but governance and due diligence need to compensate for greater dispersion in asset quality and local performance. Actual net returns depend on the building, purchase price and operating costs.
For family offices and GCC investors, portfolio construction may be more effective than selecting one apparent winner. A core allocation to Manchester, Birmingham or Leeds can provide liquidity and economic depth, while carefully selected assets in Nottingham, Sheffield or Liverpool may increase income. Institutional investors should prioritise operational scale, tenant retention, energy performance and data quality over nominal gross yield.
> Key takeaways > > – McGardens’ directional assessment places Manchester first for all-round rental growth potential. > – Birmingham and Leeds provide credible scale and diversified demand in this assessment. > – Nottingham and Sheffield offer affordability-led opportunities. > – Selected Liverpool assets may offer higher headline income, with greater asset-selection risk. > – Net income, affordability and future supply matter more than headline rent growth.
FAQ
Which UK regional city has the best rental growth potential?
McGardens’ directional assessment places Manchester first among the major regional cities considered. Its employment base, universities, graduate retention, transport network and established professional rental market support the assessment. However, outcomes vary by submarket, and investors must examine competing Build-to-Rent and apartment supply at neighbourhood level because citywide strength does not guarantee performance in every building.
Is Manchester or Birmingham better for buy-to-let?
In McGardens’ general assessment, Manchester is stronger for market depth and institutional liquidity, while Birmingham can offer a wider choice of districts and property formats. The better investment depends on purchase basis, tenant segment, service charges and nearby supply. In both cities, an established suburban house may outperform a premium new-build apartment bought at an inflated investor price.
Which regional city offers the highest rental yield?
There is no substantiated citywide answer that applies across property types and submarkets. Liverpool is often marketed as a higher-yield regional market, while selected Nottingham and Sheffield assets may also offer comparatively strong headline income. A high gross yield is not the same as a high net return: voids, management, refurbishment, service charges, licensing and weaker resale liquidity can materially reduce performance.
Are HMOs better than Build-to-Rent or standard apartments?
HMOs can generate higher gross income, but they require more intensive management and carry licensing, planning, safety and utility-cost exposure. Build-to-Rent is an institutional operating model rather than a direct substitute for a single buy-to-let unit. Standard apartments are simpler operationally, although leasehold costs and competing supply may limit returns.
Should overseas investors buy UK property through a Ltd company?
A Ltd company can be suitable for some overseas and portfolio investors, but it is not automatically tax-efficient. Corporation tax, dividend extraction, finance pricing, beneficial ownership reporting, inheritance planning and the SDLT surcharge all require review. GCC investors and family offices should obtain coordinated UK tax, legal and FCA-regulated finance advice before selecting a structure.
What data should investors use to track rental growth?
Investors should combine ONS rental indices with achieved local lettings evidence, current listings and supply-pipeline analysis. HM Land Registry helps assess sale prices, while Bank of England and RICS data provide financing and market context. Rightmove and Zoopla are useful for live asking-market signals, but asking rents should never replace evidence of signed tenancies.