UK Regional Yield Compression: What Is Driving It Right Now?
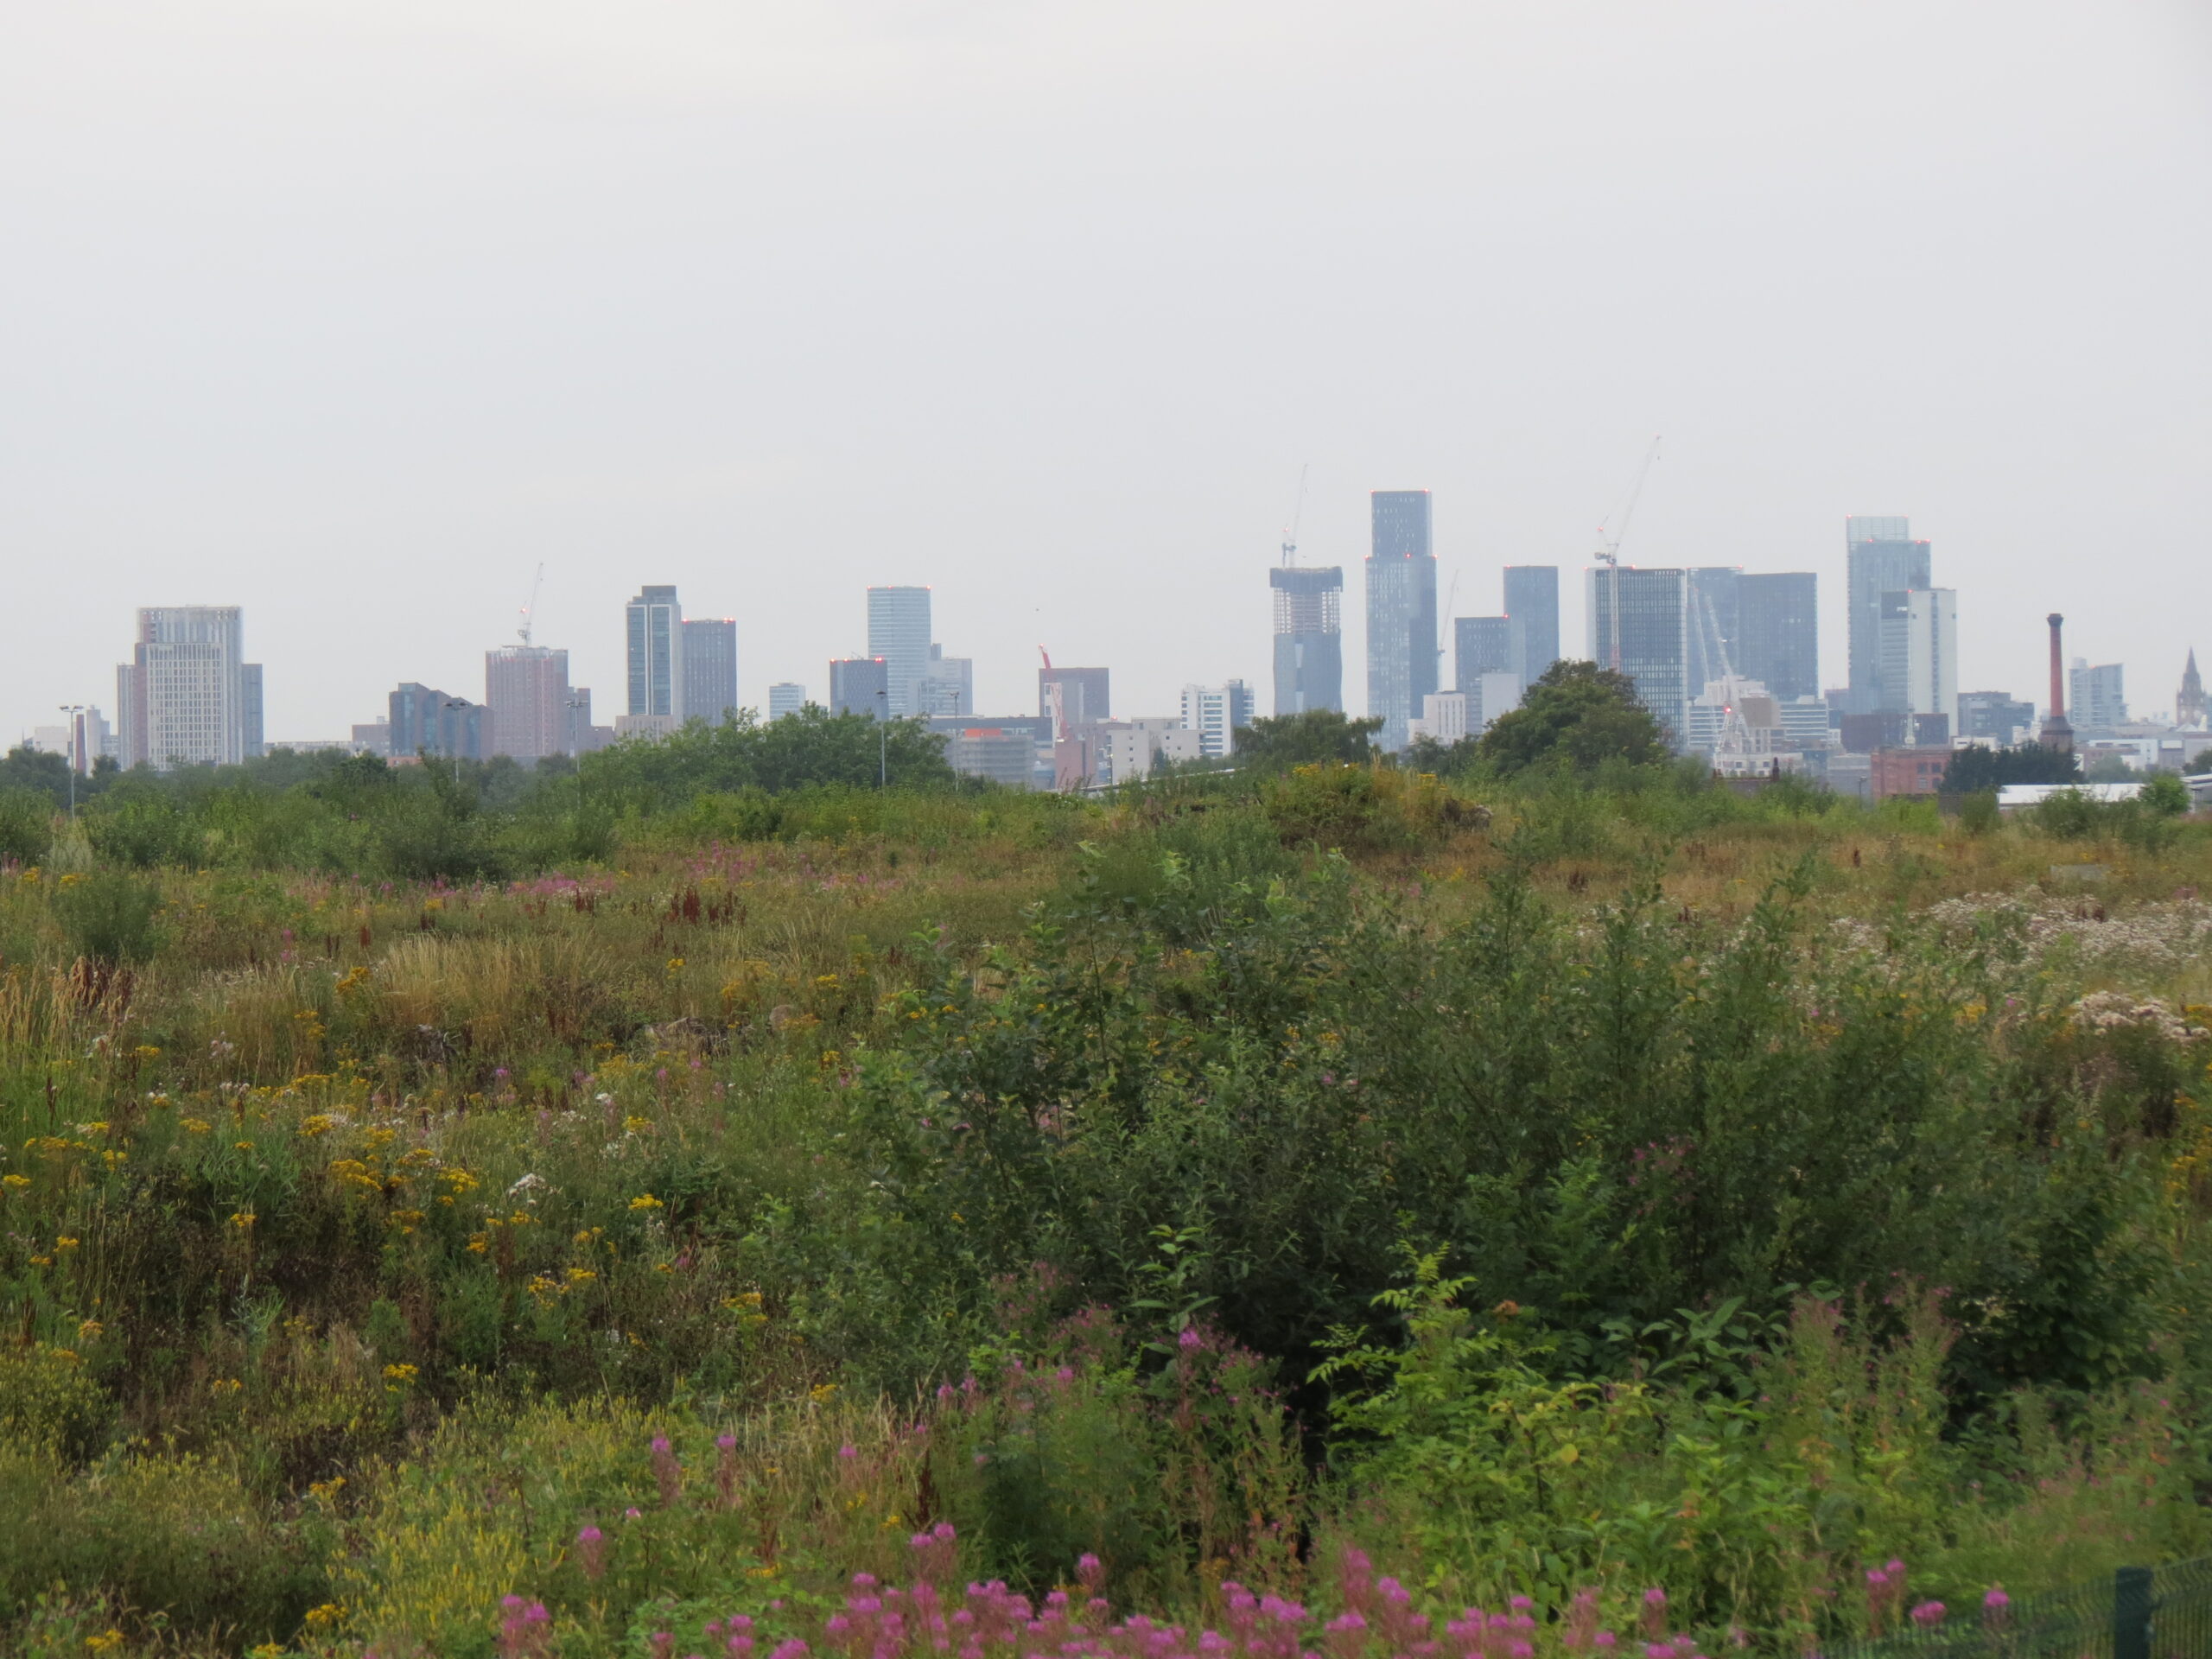
MCG’s assessment is that UK regional property yields may be compressing selectively as some investors anticipate lower financing costs, seek comparatively resilient rental income and compete for a limited supply of high-quality assets. This should not be interpreted as universal repricing: in MCG’s view, any compression is more likely to be concentrated in liquid locations and operationally sound Build-to-Rent, multifamily, PBSA and rental housing.
TL;DR
- Yield compression means an asset’s income yield falls as its price rises relative to rent.
- Improving expectations for the Bank of England base rate and debt pricing may support investor sentiment, but leverage remains asset-specific.
- MCG interprets rental growth and constrained supply as potential support for valuations in Manchester, Leeds, Birmingham and other major regional cities.
- Institutional capital is prioritising modern, energy-efficient assets with reliable occupancy and professional management.
- Secondary stock, weak locations and capital-intensive buildings may not share in any repricing.
What UK regional yield compression means
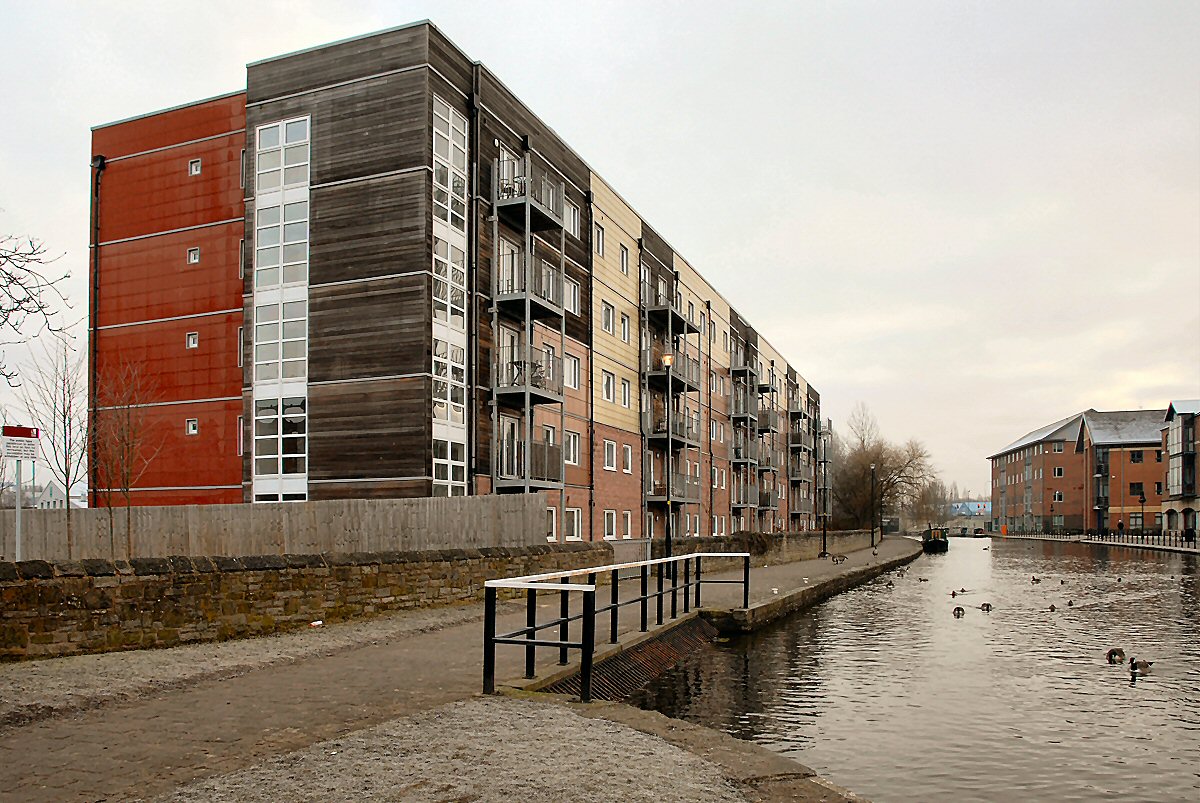
A property yield expresses annual rental income as a percentage of value. If net operating income remains unchanged while the price rises, the yield compresses. If the price falls relative to income, the yield expands.
For example, an asset producing £50,000 of annual net operating income is valued at £1 million at a 5% net yield. At a 4.75% yield, the same income supports a value of approximately £1.053 million, before acquisition costs and any allowance for capital expenditure.
| Annual net income | Applied yield | Illustrative capital value | |—:|—:|—:| | £50,000 | 5.50% | £909,091 | | £50,000 | 5.00% | £1,000,000 | | £50,000 | 4.75% | £1,052,632 | | £50,000 | 4.50% | £1,111,111 |
This sensitivity works in both directions. A small change in the exit yield can materially alter value, particularly for long-duration income assets. Investors should therefore separate genuine income growth from valuation gains created by a more aggressive yield assumption.
Yield evidence also needs careful definition. Gross residential yields exclude operating costs, while net initial yields reflect some or all purchaser costs and property outgoings. Build-to-Rent appraisals may additionally consider stabilised net operating income, lease-up costs and operational expenditure. Comparisons are meaningful only when the same methodology is used.
Why regional yields may be compressing now
1. Interest-rate expectations may be improving
The Bank of England base rate affects funding costs, required returns and the relative appeal of property against gilts and cash. Investors price assets on expected holding-period conditions rather than solely on the prevailing base rate, so improving expectations can move bids before debt becomes materially cheaper.
This does not mean the era of very low borrowing costs has returned. Lenders continue to assess interest cover, loan-to-value ratios, borrower experience, asset quality and refinancing risk. The impact is therefore likely to be strongest for assets that can support conservative leverage and predictable cash flow.
2. Rental income may provide support
MCG’s assessment is that rental income has remained comparatively resilient in parts of the UK, although the pace and level of rental growth vary by nation and region. Affordability constraints and the availability of rental stock can also differ materially between local markets.
For investors, income growth can partly offset higher operating and financing costs. Markets including Manchester, Leeds, Liverpool, Birmingham, Sheffield and Nottingham benefit from combinations of employment, universities, transport connectivity and comparatively accessible purchase prices. In MCG’s view, those fundamentals may attract both private and institutional capital.
3. Investment-grade supply may remain limited
MCG observes that the relevant constraint is not simply the availability of housing, but the availability of investment-grade housing with the required location, specification, energy performance, management platform and scale. Planning delays, elevated construction costs and viability pressures may restrict new delivery in some cities.
This scarcity can matter in Build-to-Rent, multifamily and PBSA, where institutional investors require operational evidence and often seek large assets or portfolios. When several credible bidders pursue a limited number of stabilised schemes, yields can compress even if the wider transaction market remains subdued.
4. Capital may be returning selectively
Based on current enquiries and market commentary, MCG observes that some family offices, GCC investors and institutional investors are reviewing UK regional housing following a period of price discovery. Sterling exposure, relative value against London and the ability to aggregate portfolios may be attractive to overseas buyers. Operational residential sectors may also be assessed differently from traditional commercial property because their occupier demand and income drivers differ.
In MCG’s assessment, this can produce a two-speed market. Best-in-class assets may attract competitive bidding, while poorly located or capital-intensive properties can remain difficult to finance and sell.
Where compression is most likely
Compression is more likely where an asset combines strong local demand with durable operational performance. City labels alone are insufficient: a prime transport-connected micro-location may behave very differently from peripheral stock in the same local authority.
| Market or sector | Factors supporting demand | Factors that can prevent compression | |—|—|—| | Manchester | Large employment base, graduate retention, established Build-to-Rent market | High service charges, localised supply and entry pricing | | Leeds | Financial and professional services, universities, regeneration | Uneven micro-locations and building-quality variation | | Birmingham | Scale, connectivity, corporate and student demand | Development pipeline, leasehold costs and scheme-specific risk | | Liverpool | Lower entry prices and broad tenant demand | Wide variation in neighbourhood liquidity and achieved rents | | Sheffield and Nottingham | Universities, employment nodes and relative affordability | Smaller institutional lot sizes and thinner resale evidence | | PBSA | Structural student demand in undersupplied university markets | Nomination risk, planning constraints and operating costs | | Regional Build-to-Rent | Professional management, amenity and scalable income | Lease-up risk, staffing costs and competing schemes | | HMOs | Potentially higher gross income and diversified tenancies | Licensing, Article 4 directions, management intensity and finance |
The distinction between prime and secondary assets can be important. Energy performance, fire and building-safety compliance, resident satisfaction, bad-debt control and maintenance history may influence the price investors are prepared to pay.
Build-to-Rent, PBSA and HMOs are repricing differently
Build-to-Rent vs HMOs
- Build-to-Rent: Institutional-scale, professionally operated and commonly valued using stabilised net operating income.
- HMOs: Smaller-lot, management-intensive assets whose returns depend heavily on licensing, room occupancy and local planning policy.
- Build-to-Rent: Better suited to family offices and institutions seeking scale, reporting and portfolio aggregation.
- HMOs: May offer higher headline gross yields, but compliance and operating costs can materially reduce net returns.
PBSA vs conventional rental housing
- PBSA: Demand is tied to university enrolment, international students and the quality of local accommodation supply.
- Conventional rental housing: Demand is generally broader and driven by employment, household formation and affordability.
- PBSA: Can produce resilient occupancy in structurally undersupplied cities.
- Conventional rental housing: May provide greater tenant diversification but can be harder to operate efficiently at small scale.
Yield compression should not be assumed across an entire sector. A stabilised Build-to-Rent scheme with strong occupancy and auditable costs can trade very differently from a development site. Likewise, a modern PBSA asset near a major university is not directly comparable with an older conversion facing refurbishment and energy-efficiency expenditure.
What could stop or reverse the trend
Any movement towards tighter yields would be vulnerable to changes in both the risk-free rate and property-level income. Market surveys and completed transaction evidence should be read alongside valuation-house commentary because sentiment can improve before completed sales confirm a new level.
Key risks include:
- Higher-for-longer interest rates. An adverse shift in inflation or Bank of England expectations would raise required returns and debt costs.
- Weakening rental affordability. Headline demand does not guarantee unlimited rent growth; tenant incomes impose a ceiling.
- Operating-cost inflation. Insurance, utilities, staffing, repairs and compliance can erode net income even when gross rents rise.
- Unexpected capital expenditure. Fire safety, cladding, lifts, roofs and energy upgrades can invalidate an apparently attractive yield.
- Local oversupply. New Build-to-Rent or PBSA delivery can lengthen lease-up periods and increase incentives in specific micro-markets.
- Regulatory change. Rental reform, licensing and tax treatment may affect different strategies in different ways.
- Poor exit liquidity. Smaller regional markets can have thin transaction evidence, making valuation and disposal timing less certain.
A compressed yield is therefore not automatically evidence of lower risk. It may instead reflect optimistic rental assumptions or aggressive bidding. Underwriting should test both income and exit value independently.
What overseas buyers should check from the UAE or Gulf
Non-UK-resident investors face the same property fundamentals as domestic buyers, but tax, finance and operating arrangements can materially alter the net return. GCC investors should compare structures before exchange rather than after acquisition.
Overseas-buyer checklist
- Model all SDLT layers. Residential acquisitions can attract higher rates for additional dwellings and a non-UK-resident surcharge; company and mixed-use transactions require transaction-specific advice from a UK tax professional.
- Compare personal and Ltd company ownership. Financing, corporation tax, extraction of profits, succession and disposal treatment differ. A Ltd company is not automatically the most efficient structure.
- Confirm Non-Resident Landlord Scheme treatment. Under the gov.uk scheme, letting agents or tenants may need to deduct basic-rate tax from rent unless HMRC approves gross payment.
- Secure finance early. Non-resident mortgages may require larger deposits, specialist lenders, evidence of overseas income and enhanced source-of-funds checks.
- Budget for currency risk. Sterling movements affect deposits, debt servicing and repatriated returns.
- Appoint accountable UK management. Remote ownership requires reliable rent collection, inspections, compliance, maintenance procurement and financial reporting.
- Verify FCA boundaries. Property itself is generally not FCA-regulated in the same way as a regulated investment product, but finance and collective-investment arrangements may fall within regulated activities.
Professional legal and tax advice remains essential. Yield comparisons should be made after SDLT, finance, tax, management, service charges, voids and maintenance—not on the advertised gross figure alone.
McGardens’ view
McGardens Estate (MCG) is a UK real estate investment and management firm advising family offices, GCC and overseas private capital and institutional investors, and managing UK rental portfolios for overseas landlords.
MCG’s assessment is that UK regional yield compression may be real but narrow. The market does not appear to be rewarding regional exposure indiscriminately; in MCG’s view, it is more likely to reward defensible income, strong micro-locations, credible operating data and assets that do not conceal major capital liabilities.
For family offices, the opportunity is less about predicting the next base-rate decision and more about buying income that can compound. Portfolios assembled across Manchester, Leeds, Birmingham and selected secondary cities can diversify tenant and employment exposure, but only if management information is standardised and local risks are understood.
For institutional capital, operational evidence can be a pricing advantage. Occupancy alone is insufficient: bidders may also require cohort-level renewals, arrears, incentives, maintenance costs, utility consumption and resident retention. A scheme with slightly lower headline rent but stronger net operating margins may deserve the tighter yield.
The principal underwriting error would be to capitalise short-term rental growth indefinitely while also assuming substantial exit-yield compression. A more defensible case uses moderate income growth, explicit capital expenditure and a flat or softer exit yield. Compression should be treated as upside, not as the mechanism required to make an acquisition work.
> Key takeaways > > – MCG’s assessment is that any UK regional yield compression is likely to be concentrated in scarce, liquid and operationally strong assets. > – Interest-rate expectations may act as a catalyst, while rental resilience and limited supply may provide underlying support. > – Prime and secondary stock can diverge, even within the same city. > – Overseas buyers must assess SDLT, the Non-Resident Landlord Scheme, currency exposure and remote management. > – Investment cases should remain viable without assuming further yield compression.
FAQ
Are UK regional property yields falling now?
MCG’s assessment is that UK regional property yields may be falling selectively rather than universally. Better-quality Build-to-Rent, PBSA and professionally managed rental assets may attract tighter pricing where income is resilient and supply is scarce. Secondary buildings, weaker micro-locations and properties requiring major expenditure may see little compression or may still reprice outward.
Which UK regional cities are attracting investor demand?
In MCG’s experience, Manchester, Leeds, Birmingham and Liverpool are prominent regional investment markets, with Sheffield and Nottingham also attracting interest. Demand varies substantially within each city, so transport access, employment nodes, university exposure, local pipeline and building quality are more informative than a city-wide average yield.
Do lower interest rates always cause property yields to compress?
Lower interest rates do not automatically cause property yields to compress. They can reduce debt costs and required returns, but pricing also depends on rental growth, liquidity, risk-free rates, lender appetite and asset quality. Property yields may remain high if income is uncertain or substantial capital expenditure is required.
Is a high-yield HMO better than Build-to-Rent?
A high-yield HMO is not necessarily better than Build-to-Rent. HMOs can generate stronger headline income but require intensive management and careful review of licensing, Article 4 restrictions, fire safety and occupancy. Build-to-Rent usually offers greater scale and reporting consistency, although its amenity and staffing costs must be reflected in net income.
What changes when buying UK rental property from the UAE?
A UAE-based buyer must account for non-resident tax and finance considerations. These can include the non-UK-resident SDLT surcharge, the Non-Resident Landlord Scheme, specialist mortgage requirements, currency exposure and enhanced source-of-funds checks. UK-based property management is also important for compliance, rent collection, inspections and maintenance.
How should investors underwrite yield compression?
Investors should not rely on yield compression to justify an acquisition. A prudent appraisal tests sustainable net income, voids, management, service charges, financing and capital expenditure, then models a flat or softer exit yield. Any value gain from a tighter market yield should be treated as upside rather than a base-case assumption.